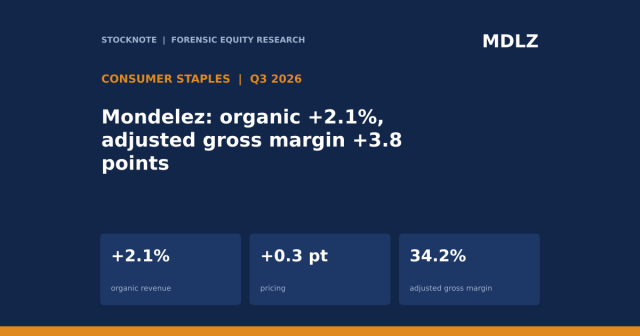
Mondelez's Q3 2026 Profit Jump Came From Lower Costs, Not Sales Growth
Mondelez's Q3 2026 organic growth was 2.1%, with pricing at 0.3 points, while adjusted gross margin rose 3.8 points and about 85% of the gross profit gain came from margin.
Research on consumer staples sector companies including food, beverages, and household products.
Mondelez's Q3 2026 organic growth was 2.1%, with pricing at 0.3 points, while adjusted gross margin rose 3.8 points and about 85% of the gross profit gain came from margin.
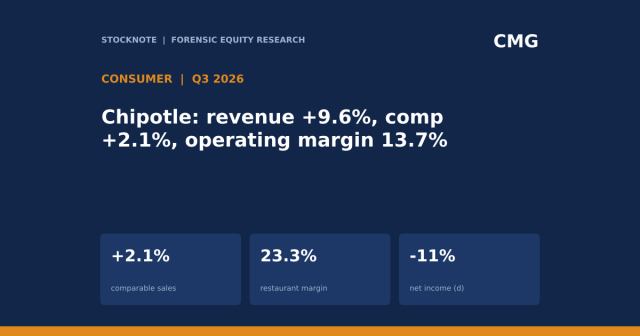
Philip Morris's Q3 2026 organic revenue grew 7.1%, led by combustibles pricing (+7.8%) on flat cigarette volume, while international smoke-free grew 3.4% organically.
Chipotle's Q3 2026 revenue rose 9.6% on 2.1% comparable sales and 9% more restaurants, but labor, occupancy and other costs outgrew revenue, cutting operating margin to 13.7%.
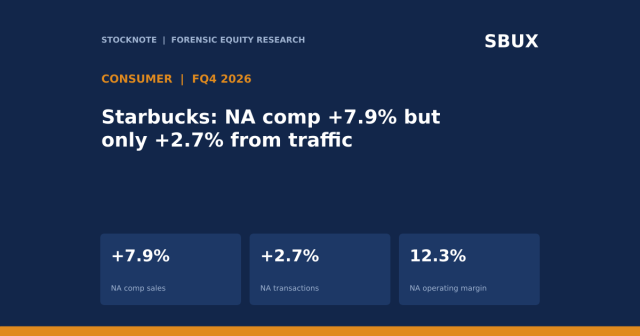
Starbucks' fiscal Q4 2026 North America comparable sales rose 7.9% (ticket +5%, transactions +2.7%) with a 12.3% margin, while international traffic fell 2.8% and consolidated revenue fell 4%.
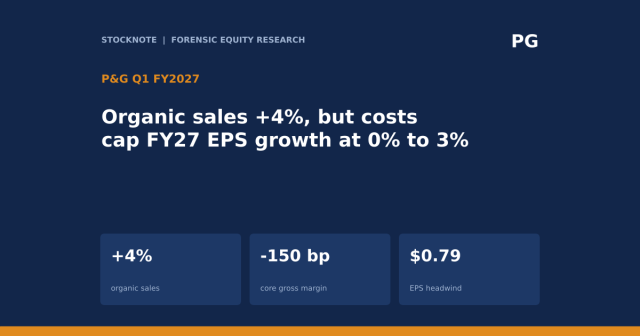
P&G's fiscal Q1 organic sales rose 4% on volume and mix with little price, but core gross margin fell 150 basis points and the FY27 cost and currency headwind rose to $0.79 a share.
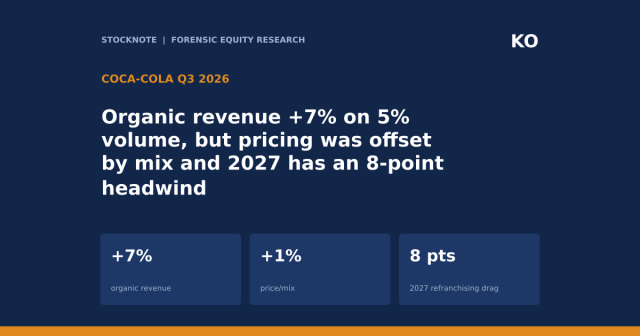
Coca-Cola grew Q3 organic revenue 7% on volume, but price/mix was only 1%, currency added 2 points to EPS and early 2027 faces an 8-point refranchising headwind.
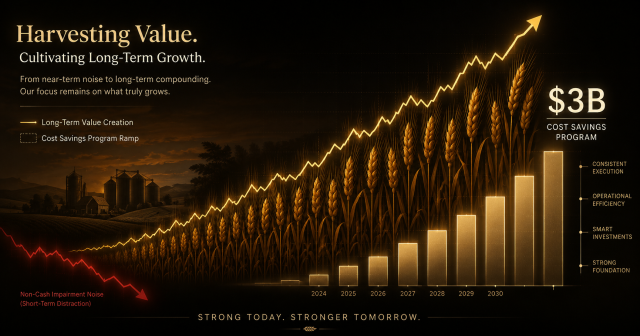
General Mills’ Q4 FY2026 adjusted EPS beat consensus by 15.9% and the company launched a $3B cumulative cost savings program — both buried under a $2.1B non-cash goodwill impairment. The real business is inflecting positively; the GAAP headline is accounting noise.
Kraft Heinz's 7.1% dividend yield is pricing in a cut that 1.9x free cash flow coverage doesn't support. New CEO Steve Cahillane's $600M investment cycle follows the same playbook that worked at Kellogg's.
Conagra's 11% dividend yield is pricing in a B&G Foods-style halving — but Conagra runs at 3.8x leverage versus B&G's 6-8x, and Q3 organic sales just returned to growth led by Frozen and Snacks.
Altria has re-rated 27% to ~$72, yet still trades at 13x against a 19x historical average while consensus prices three demonstrably wrong calls: a "volume cliff" offset by relentless pricing power, a smoke-free option marked near zero after NJOY, and a ~$9B ABI stake buried by single-multiple math. Forensic case: BUY, $82 in 12 months, $95+ long-term.
Hershey trades at 19x forward earnings versus a 10-year median of 26x, while consensus prices in three demonstrably wrong assumptions about cocoa, GLP-1s, and Salty Snacks. The forensic case points to $235 in 12 months and $275+ longer term. Option 2 — Contrarian hook The market thinks GLP-1s will hurt chocolate demand — peer-reviewed Cornell data shows the opposite. Combined with the cocoa hedge lag and an unmodeled Salty Snacks asset, Hershey's mispricing is measurable, falsifiable, and worth 25%+ upside.
Forensic equity research on US stocks. No spam, unsubscribe anytime.