American Express's GAAP EPS Rose 31% But Adjusted Pretax Income Only 1.6%
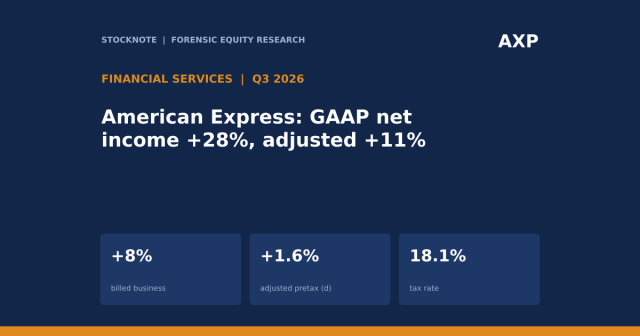
American Express's Q3 2026 revenue rose 9% and adjusted EPS 13%, but adjusted pretax income grew about 1.6% as the tax rate fell to 18.1% and provisions eased.

Banks, insurance, asset managers, and fintech analysis.
American Express's Q3 2026 revenue rose 9% and adjusted EPS 13%, but adjusted pretax income grew about 1.6% as the tax rate fell to 18.1% and provisions eased.
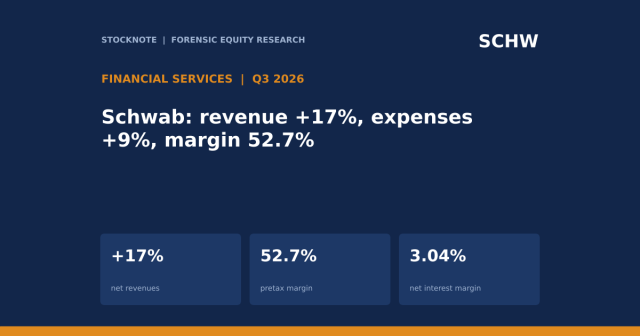
Schwab's Q3 2026 net revenues rose 17% on 9% higher expenses (pretax margin 52.7%), while net interest revenue was driven by volume and margin and borrowings rose about 45%.
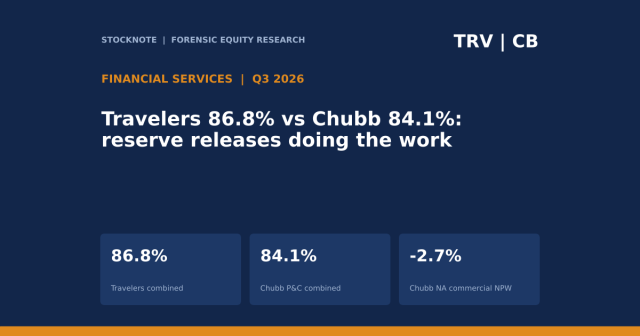
Travelers and Chubb reported combined ratios of 86.8% and 84.1% in Q3 2026, but favorable reserve releases, catastrophe losses and softer commercial premiums change the quality of those results.
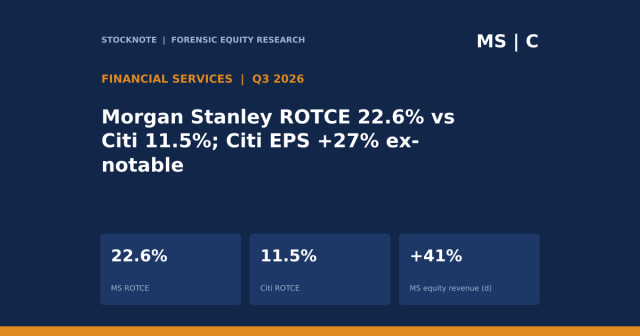
Morgan Stanley earned a 22.6% ROTCE in Q3 2026 against Citigroup's 11.5%; Citi's net income rose 40% but excluding a $726M year-ago impairment EPS rose 27%.
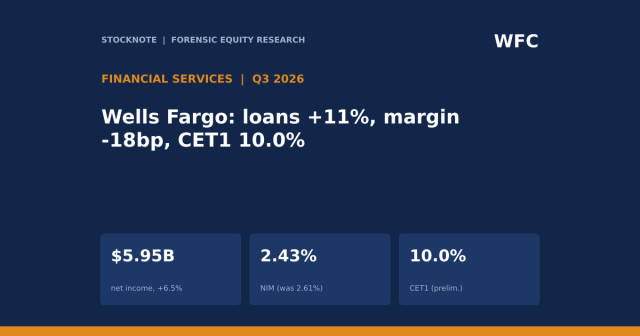
Wells Fargo's Q3 2026 EPS rose 12.7% on 2.0% revenue growth: loans grew 11.3% but net interest margin fell 18bp, with expenses and tax lower and CET1 down to 10.0%.
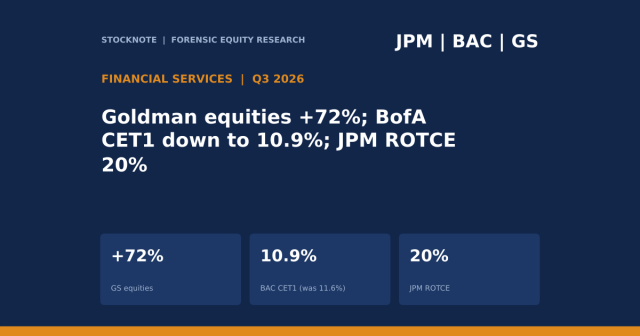
In Q3 2026 Goldman's equities revenue rose 72% and trading was 53% of its revenue, while Bank of America's CET1 fell to 10.9% and JPMorgan earned a 20% ROTCE.
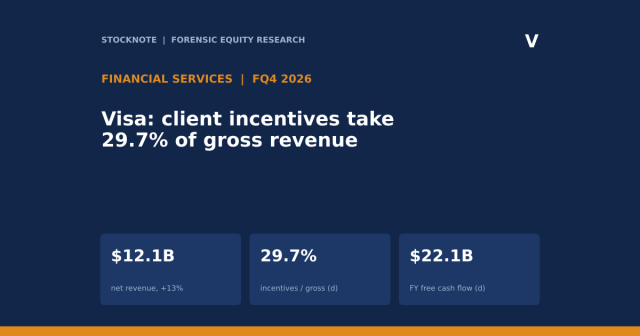
Visa's client incentives took 29.7% of gross revenue in fiscal Q4 2026 and grew 21% against net revenue +13%, while FY buybacks and dividends of $25.6B exceeded $22.1B of free cash flow.
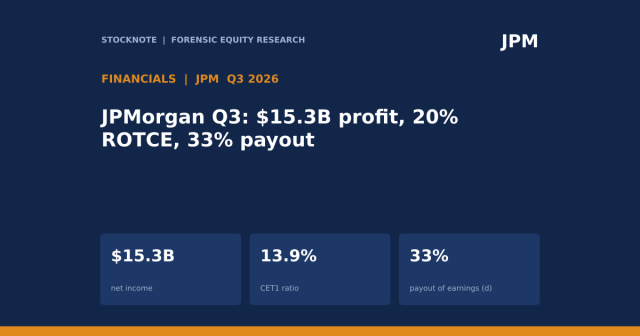
JPMorgan earned $15.3B in Q3 2026 with 53% of revenue from interest income, a 54% overhead ratio and only a 33% payout, holding a 13.9% CET1 ratio while loans grew 10%.
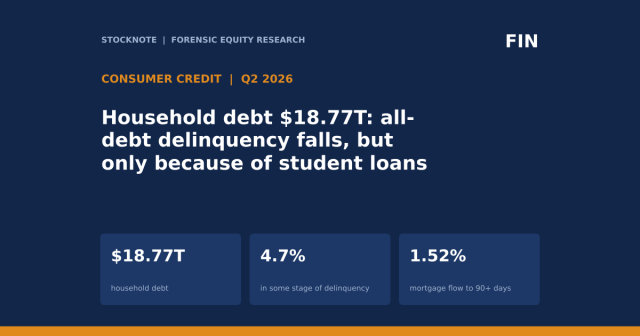
US household debt reached $18.771T at June 30, 2026 and the all-debt flow into serious delinquency fell to 2.57%, but student loans drove the improvement while mortgage flows rose.
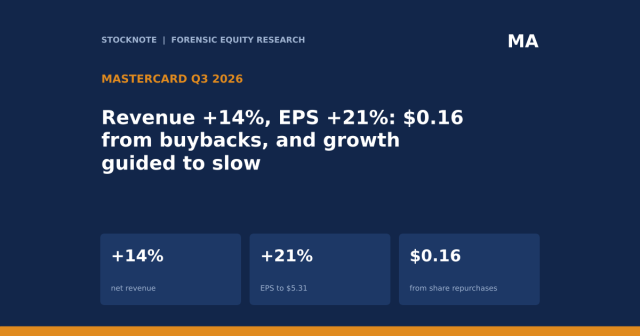
Mastercard grew Q3 EPS 21% to $5.31, but buybacks supplied $0.16 and management guided Q4 revenue and expense growth to the same rate.
Visa beat estimates and raised its dividend 16%, but client incentives grew 21%, costs matched revenue growth, and free cash flow rose 2% on 17% profit growth.
Revenue grew 12% to a record $1.42B, but GAAP EPS fell 16%. Event contracts replaced crypto, the tax rate doubled, and Q4 costs are guided 15% to 26% higher.
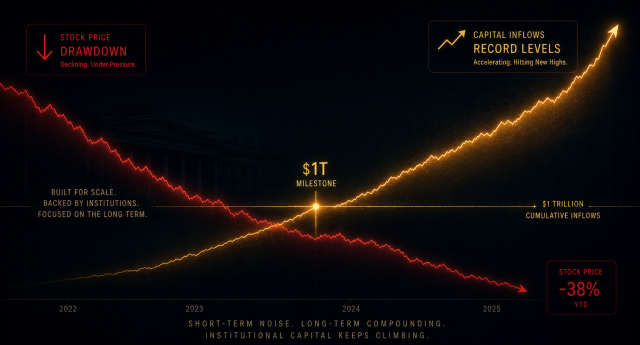
Apollo posted record $728M Fee Related Earnings and crossed $1 trillion in AUM in Q1 2026. A 40-60% valuation discount to peers versus 30% FRE growth makes no fundamental sense.
Citigroup's Q1 RoTCE of 13.1% already cleared its 2026 target, and the bank is buying back stock near tangible book value of $99.01 — yet it still trades like an unfinished turnaround.
PYPL has de-rated to ~$44 and ~8.4x earnings on a single fear — branded checkout is losing share — while consensus misprices three things the filings refute: a ~$14B transaction-profit base growing 3% in spite of the checkout drag, a Venmo/PSP growth engine compounding double digits, and a ~$6B annual buyback retiring ~10% of the float a year. Forensic case: BUY, $62 in 12 months, $80+ long-term.
Forensic equity research on US stocks. No spam, unsubscribe anytime.