
Investment Thesis
UnitedHealth beat Q3 adjusted EPS by about $0.55 and raised its 2026 guide for the third time, but a $610M favorable reserve release is worth roughly $0.53 per share, revenue and membership are shrinking, and debt-to-capital rose in the quarter.
- Earnings. Revenue was $112.7B (-0.4%), earnings from operations were $6,563M (+52%), and adjusted EPS was $4.69 vs $2.92 (+61%), against $4.12 to $4.14 expected. GAAP EPS was $4.56 vs $2.59 (+76%).
- Reserve release. The medical care ratio improved to 88.4% from 89.9%. The release reports $610M of net favorable reserve development in Q3. After tax that is about $0.53 per share and 0.7 points of the ratio (derived), against a beat of about $0.57 over the $4.12 estimate.
- Shrinking book. Premiums fell 2.1% and UnitedHealthcare medical membership fell 3.6% in a year to 48.3M. Medicare Advantage fell 840,000 and Medicaid 685,000 since December (derived). Optum Health revenue fell 9.9%.
- Profit mix. Operating earnings rose $2,248M. UnitedHealthcare added $1,026M and Optum Health $694M, from a base of $41M a year ago. GAAP operating earnings also include $298M of net gains and other items that adjusted results remove (derived).
- Guidance. Adjusted EPS guidance is now "at least $20.50", from $19.50 to $20.00. Nine-month adjusted EPS is $18.30, so the guide implies at least $2.20 in Q4, 53% below Q3's $4.69 (derived).
- Balance sheet. Debt-to-capital was 41.7% at Sept 30, up from 41.2% at June 30, against a goal of about 40% by year end. Nine-month dividends and buybacks of $11.2B took 49% of free cash flow (derived).
- Stock. It closed at $377.76 on Oct 13 (-0.2%) and $395.62 on Oct 14 (+4.7%), per a secondary source. At $395.62 it is about 19.3x guided adjusted EPS (derived).
- This article contains no price target or rating. Every figure comes from UnitedHealth's release or a named source, and anything I calculated is marked.
Source: UnitedHealth Group Q3 2026 earnings release, Exhibit 99.1 to Form 8-K, Oct 13, 2026.
Q3 2026 At A Glance
Revenue was flat at $112.7B, but earnings from operations rose 52% and the medical care ratio fell 1.5 points.
| Metric (quarter ended Sept 30) | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Total revenues | $112,694M | $113,161M | -0.4% (d) |
| Premiums | $87,078M | $88,979M | -2.1% (d) |
| Medical costs | $76,982M | $79,958M | -3.7% (d) |
| Medical care ratio | 88.4% | 89.9% | -1.5 pts |
| Operating cost ratio | 12.8% | 13.5% | -0.7 pts |
| Earnings from operations (GAAP) | $6,563M | $4,315M | +52% (d) |
| Earnings from operations (adjusted) | $6,265M | n/a | Margin 5.6% |
| Net earnings to UnitedHealth shareholders | $4,110M | $2,348M | +75% (d) |
| Diluted EPS (GAAP) | $4.56 | $2.59 | +76% (d) |
| Adjusted EPS | $4.69 | $2.92 | +61% (d) |
| Days claims payable | 47.0 | 46.2 | +0.8 |
| UnitedHealthcare medical members | 48.3M | 50.1M | -3.6% (d) |
| Interest expense | $963M | $1,003M | -4% (d) |
| Effective tax rate | 22.2% | 21.2% | +1.0 pt (d) |
(d) = derived. The release does not give Q3 2025 adjusted earnings from operations. Source: UnitedHealth Q3 2026 earnings release.
What The Market Believes vs. What The Data Actually Shows
UnitedHealth beat on revenue, adjusted EPS and the medical care ratio and raised guidance, but the stock closed slightly lower on the day and rose the next session.
| Item | Result or guide | Comparison |
|---|---|---|
| Adjusted EPS | $4.69 | $4.12 (XTB, Zacks) to $4.14 (Reuters via Tradingpedia) expected |
| Revenue | $112.69B | $111.03B expected (XTB), +1.5% (derived) |
| Medical care ratio | 88.4% | 89.9% expected per XTB, which matches last year's actual |
| Operating cost ratio | 12.8% | 12.6% expected (XTB) |
| UnitedHealthcare medical members | 48.3M | 48.62M expected (XTB) |
| 2026 adjusted EPS | At least $20.50 | Raised from $19.50 to $20.00; consensus $19.86 (LSEG) |
| 2026 GAAP EPS | At least $19.50 | Raised from $18.45 to $18.95 (XTB) |
Price reaction: UnitedHealth traded about 2% to 3% higher before the open on Oct 13 ($386.90 premarket, Tradingpedia). A secondary source reports it closed down 0.23% on earnings day at $377.76, then rose 4.73% to $395.62 on the next session on 7.8M shares against a 30-day average of 5.5M. I could not check the Oct 13 and Oct 14 closes against an exchange source, and the prices will have moved since. The same source gives a 52-week range of $255.97 to $461.62, which puts $395.62 14% below the high (derived).
Commentary that bears on the quality of the beat: Zacks says commercial medical cost trends remain above the company's initial 11% expectation, and 24/7 Wall St. says shrinking membership and the $610M favorable reserve development may not repeat. The CFO said the low end of the 13% to 16% long-term earnings growth target is a reasonable starting point for 2027, with a fuller 2027 outlook promised before year end (Zacks, as reported by HeyGoTrade). I did not read the call transcript.
Sources: UnitedHealth Q3 2026 earnings release; XTB; Tradingpedia; HeyGoTrade.
Forensic #1: A $610M Reserve Release Is Worth About $0.53 Of The $0.57 Beat
The medical care ratio fell 1.5 points, and part of that comes from reserves set aside earlier.
| Q3 2026 item | Amount |
|---|---|
| Net favorable reserve development (release) | $610M |
| Share of premiums ($87,078M) | 0.7 pts (d) |
| Medical care ratio as reported | 88.4% |
| Medical care ratio without the $610M, if nothing else changed | about 89.1% (d) |
| After-tax value at the 22.2% quarterly rate | about $475M (d) |
| Per diluted share (902M shares) | about $0.53 (d) |
| Adjusted EPS beat versus $4.12 consensus | $0.57 (d) |
(d) = derived. Adjusted EPS includes the reserve development. I do not know how much of it analysts had already assumed, and the release does not give the prior-year Q3 figure, so the 0.7 point effect is not a like-for-like year-over-year bridge. Source: UnitedHealth Q3 2026 earnings release; my arithmetic.
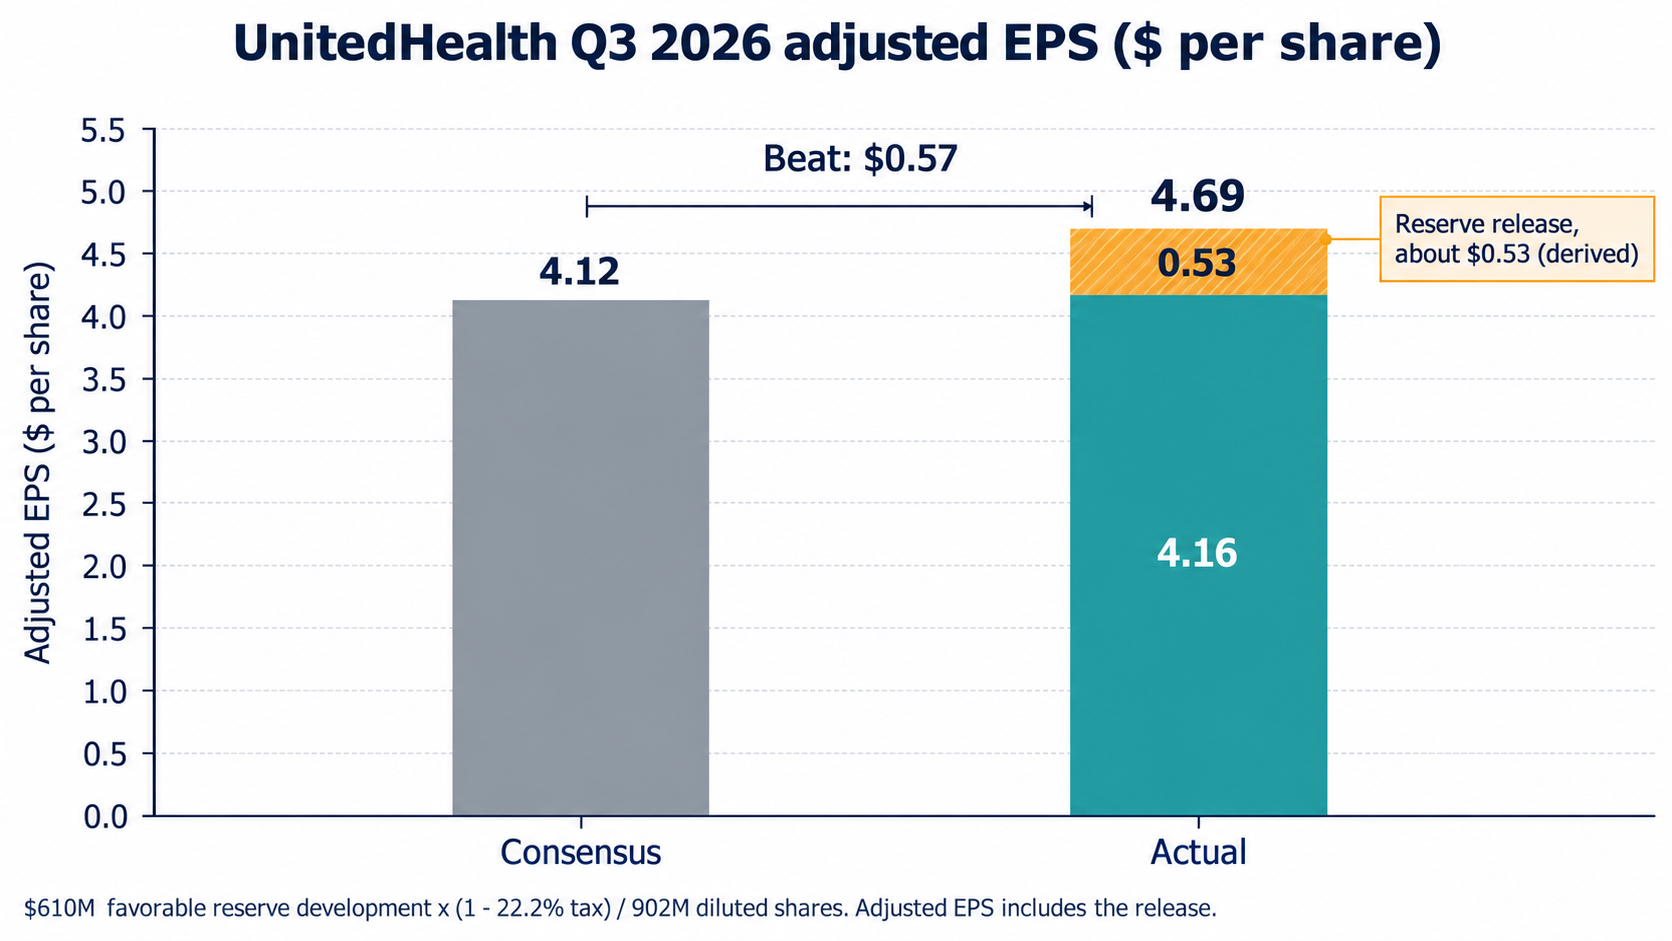
Q3 2026 Adjusted EPS vs Consensus, With The Estimated Value Of The Reserve Release (Self-Made)
The release describes the $610M as related to 2026 dates of service, while the label calls it prior-period development, so the wording is ambiguous. Q3 also included a net decrease in loss contract reserves of $95M ($282M for nine months). The release says adjusted EPS for the full year excludes the net decrease in loss contract reserves and does not give the amount. Days claims payable were 47.0, the same as in Q2 and up from 46.2 a year ago, and medical costs payable were flat at $39,352M against $39,337M at December 31.
The operating side improved too. The operating cost ratio fell to 12.8% from 13.5%, and GAAP operating cost fell 5.6% to $14,369M. The release also reports a $400M United Health Foundation contribution in the nine-month figures, funded by a gain on disposing of an Optum Insight business; it does not say which quarter it fell in.
Sources: UnitedHealth Q3 2026 earnings release; XTB for the $4.12 estimate.
Forensic #2: Earnings Rose 52% While Revenue And Membership Fell
UnitedHealth is earning more from a smaller book of business.
| People served (thousands) | Sep 30, 2026 | Dec 31, 2025 | Change since December |
|---|---|---|---|
| Commercial, risk-based | 7,575 | 8,165 | -590 (-7.2%) (d) |
| Commercial, fee-based | 22,180 | 21,485 | +695 (+3.2%) (d) |
| Medicare Advantage | 7,605 | 8,445 | -840 (-9.9%) (d) |
| Medicaid | 6,695 | 7,380 | -685 (-9.3%) (d) |
| Medicare Supplement | 4,245 | 4,285 | -40 (-0.9%) (d) |
| UnitedHealthcare medical total | 48,300 | 49,760 | -1,460 (-2.9%) (d) |
(d) = derived. Source: UnitedHealth Q3 2026 earnings release.
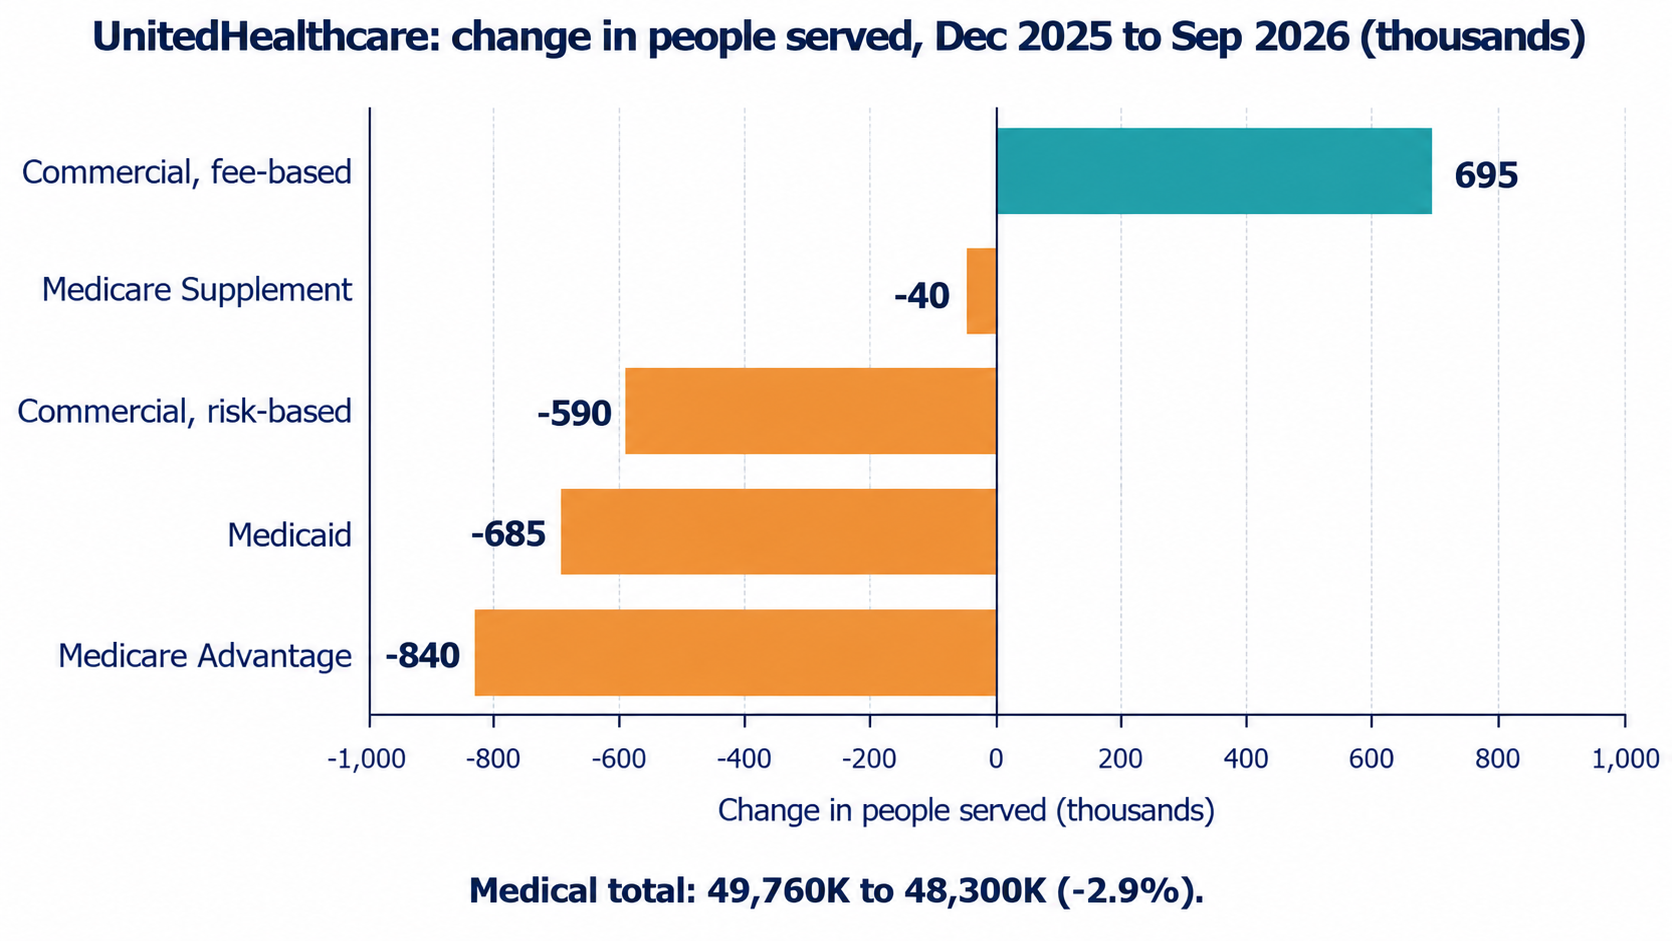
Change In UnitedHealthcare Members By Product, Dec 31, 2025 To Sep 30, 2026, Thousands (Self-Made)
Fee-based commercial members grew while every risk-bearing category shrank. UnitedHealthcare revenue fell 0.9% to $86,330M while its earnings from operations rose 57% to $2,831M, a margin of 3.3% against 2.1% (derived). Medicare and Retirement revenue fell to $42,420M from $43,356M, and Optum Health revenue fell 9.9% to $22,910M while its operating earnings rose to $735M from $41M. The number of consumers Optum Health serves slipped to 92M from 93M a year ago.
Healthcare Dive reports that UnitedHealthcare expects to lose more than 1 million Medicare Advantage members in 2026, expects to end the year at the high end of its 2% to 4% Medicare Advantage margin range, and cut "hundreds" of Medicare Advantage plans for 2027. It says the share of members in plans rated 4 stars or more is set to fall to 68% in 2027 from 81% in 2026, with management targeting about 75% by year end 2027. It also reports a 2026 Medicaid margin of about -1%. These are from a news summary, not the release.
The release's text says seniors contracted by 935,000 since year end, including complex Medicaid populations. The table shows Medicare Advantage down 840,000 and Medicaid down 685,000, and I could not reconcile the 935,000 with it.
Sources: UnitedHealth Q3 2026 earnings release; Healthcare Dive.
Forensic #3: Where The Extra $2.2B Of Operating Earnings Came From, And What Q4 Implies
Three of four segments grew earnings, and the guide points to a much lower Q4.
| Earnings from operations | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| UnitedHealthcare | $2,831M | $1,805M | +$1,026M (+57%) (d) |
| Optum Health | $735M | $41M | +$694M (d) |
| Optum Insight | $1,279M | $920M | +$359M (+39%) (d) |
| Optum Rx | $1,718M | $1,549M | +$169M (+11%) (d) |
| Consolidated | $6,563M | $4,315M | +$2,248M (+52%) (d) |
(d) = derived. Segment figures are GAAP and sum to the consolidated total. Source: UnitedHealth Q3 2026 earnings release.
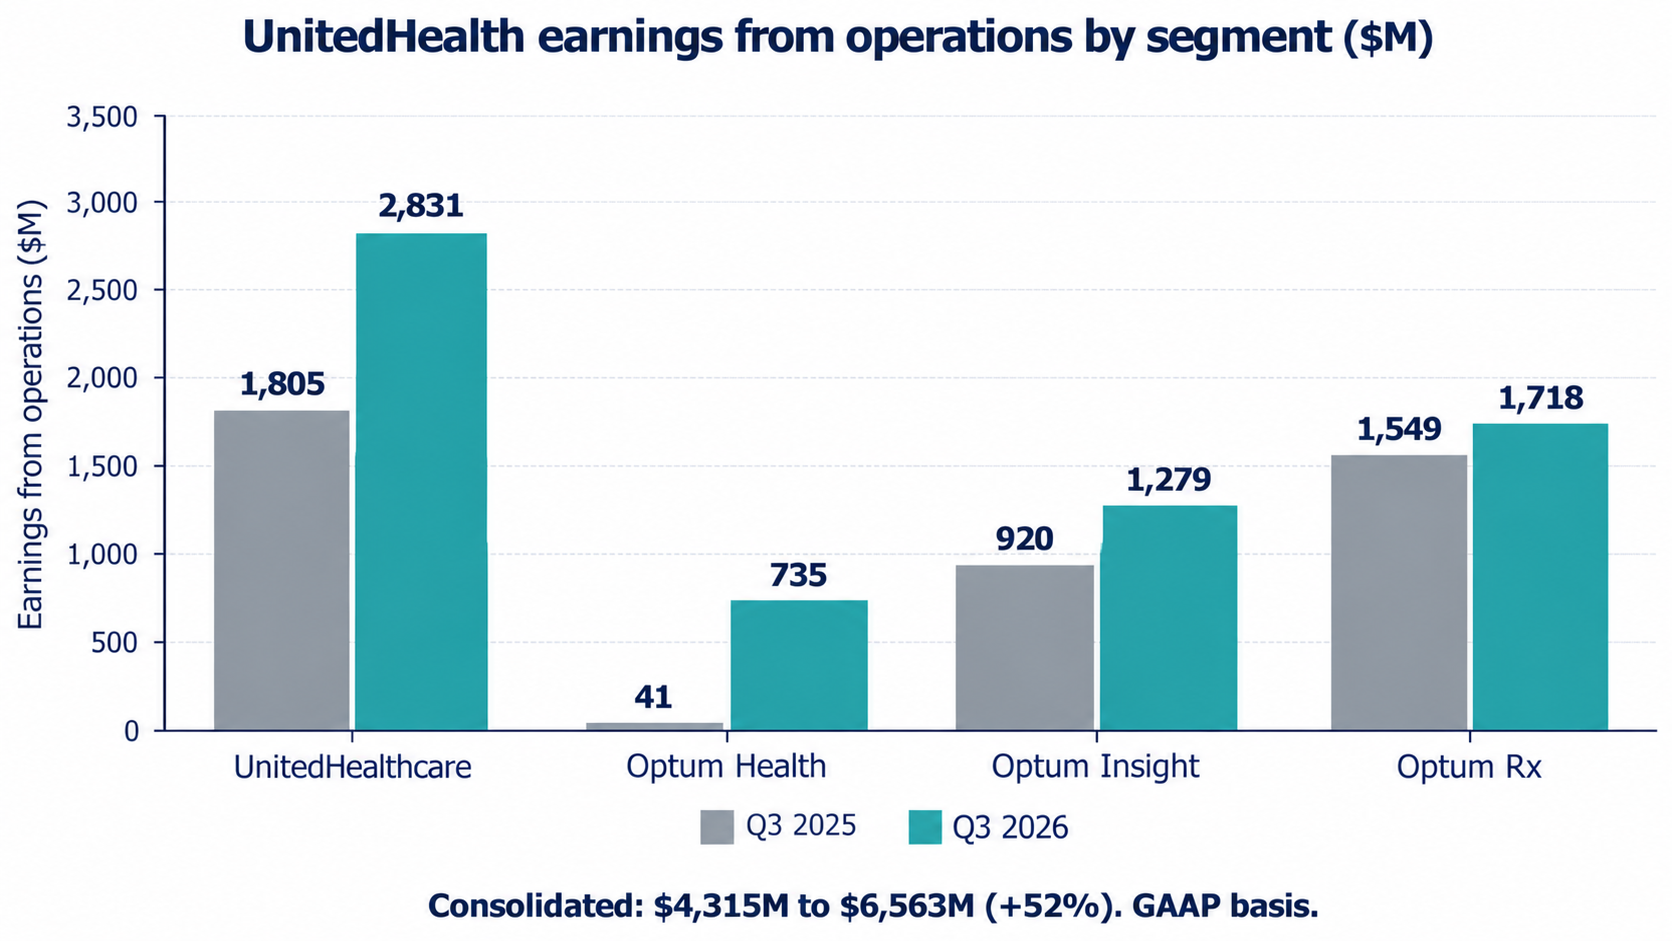
Earnings From Operations By Segment, Q3 2026 vs Q3 2025, $M (Self-Made)
UnitedHealthcare and Optum Health together provide $1,720M of the $2,248M increase, 77% (derived). Optum Health's adjusted earnings were $588M (a 2.6% margin), $147M below its GAAP figure, and UnitedHealthcare's adjusted figure was $141M below GAAP. Across the company the gap between GAAP and adjusted earnings from operations is $298M, made up of $224M of net portfolio divestiture and South American items and $74M of restructuring and other (derived from the reconciliation). Adjusted net earnings rose 59.5% to $4,228M. GAAP EPS of $4.56 is $0.13 below adjusted EPS: intangible amortization adds $0.41, and portfolio items, restructuring and tax take away $0.16, $0.08 and $0.04.
The guide is the other half of the picture. Adjusted EPS guidance of at least $20.50 less nine-month adjusted EPS of $18.30 leaves at least $2.20 for Q4, which is 53% below Q3's $4.69 (derived). The GAAP guide of at least $19.50 less $17.50 implies at least $2.00, 56% below Q3 (derived). The wording is "at least", so Q4 could come in higher. The release does not explain the step down, and it gives no guidance for revenue, the medical care ratio or operating cash flow.
Sources: UnitedHealth Q3 2026 earnings release.
Forensic #4: Debt-To-Capital Rose To 41.7% While Shareholders Took 49% Of Free Cash Flow
Cash flow is strong, but the deleveraging goal moved the wrong way in Q3.
| Nine months ended Sept 30 | 2026 | 2025 | Change |
|---|---|---|---|
| Cash flows from operating activities | $25,087M | $18,589M | +35% (d) |
| Purchases of property, equipment and software | $2,421M | $2,674M | -9% (d) |
| Operating cash flow minus capex | $22,666M | $15,915M | +42% (d) |
| Dividends paid | $6,170M | $5,914M | +4% (d) |
| Common share repurchases | $5,031M | $5,545M | -9% (d) |
| Net repayment of debt (2025: net borrowing) | $3,075M | -$2,438M | n/m |
| Repayment of care provider loans (cyberattack) | $282M | $1,543M | -82% (d) |
(d) = derived. Operating cash flow minus capex is my measure, not a company figure. Source: UnitedHealth Q3 2026 earnings release.
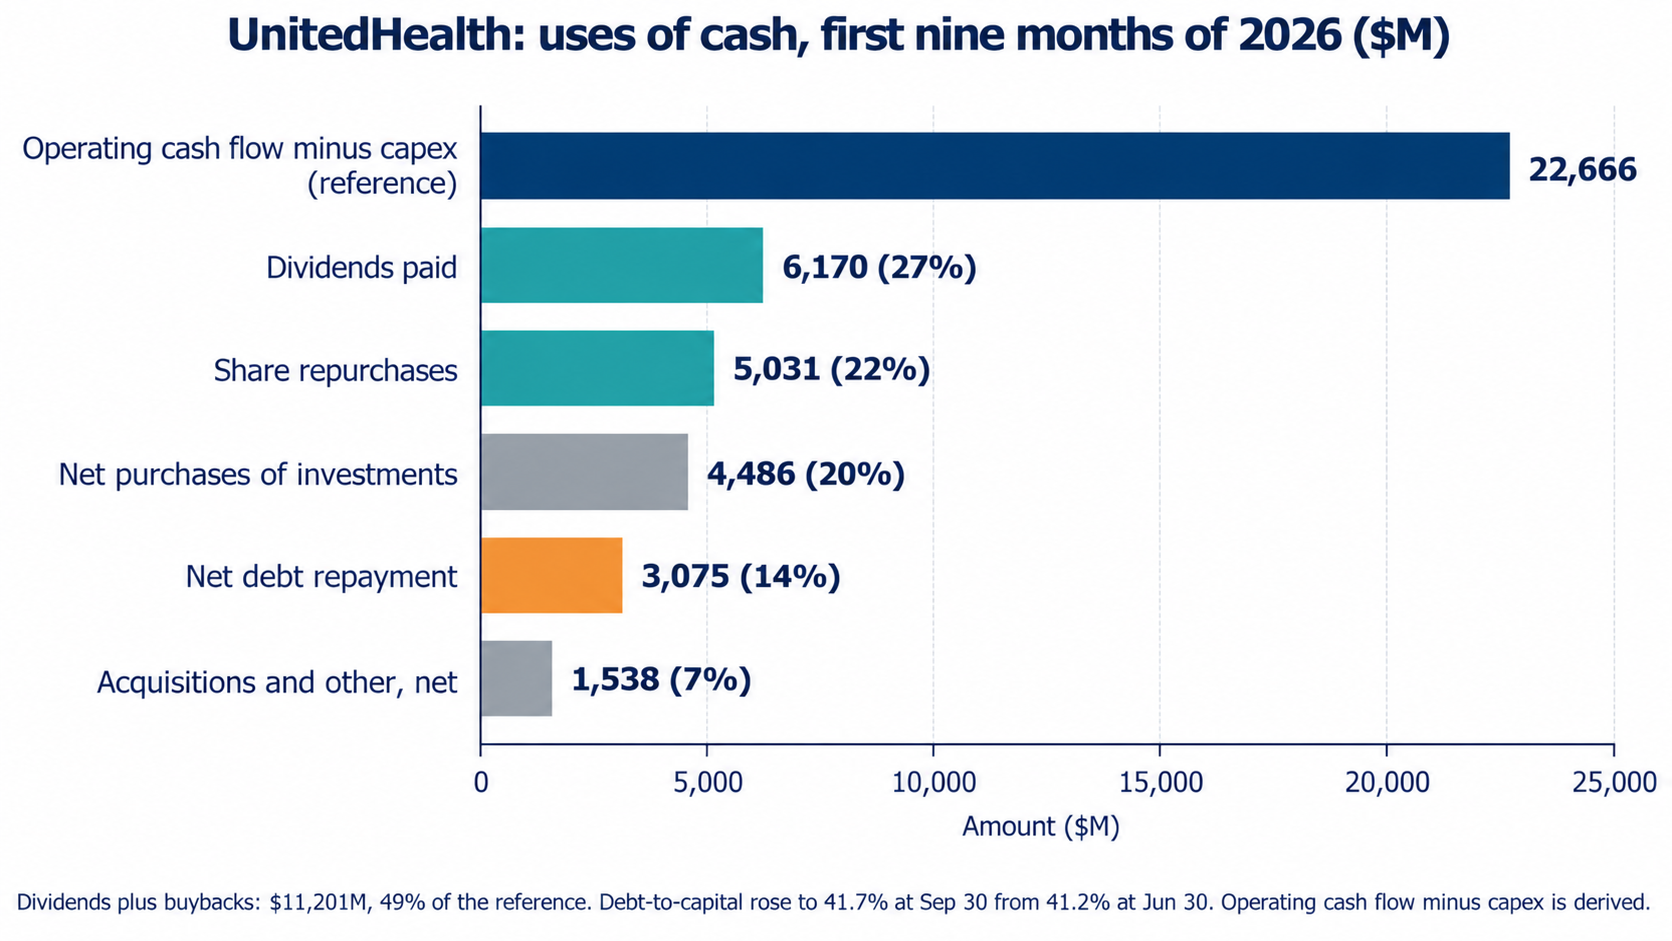
Nine-Month Uses Of Cash vs Operating Cash Flow Minus Capex, 2026, $M (Self-Made)
Dividends and buybacks together were $11,201M, 49% of the $22,666M (derived). Net debt repayment took another 14%, and net purchases of investments took 20% (derived). Total debt fell 5.2% to $74,331M from $78,389M (derived), but debt-to-capital rose to 41.7% at Sept 30 from 41.2% at June 30. The target is about 40% by year end. The release does not explain the rise.
Operating cash flow growth owes a good part to working capital. Net changes in operating assets and liabilities contributed $4,327M against $2,777M a year ago, an increase of $1,550M that is 24% of the $6,498M rise in operating cash flow (derived). Net earnings account for 59% of the rise (derived). Q3 operating cash flow was $5.1B, 1.2 times net income. Accounts receivable fell to $20,543M from $23,018M at year end, and days sales outstanding were 16.9 against 18.6 a year ago.
Sources: UnitedHealth Q3 2026 earnings release.
Valuation Snapshot
At $395.62, UnitedHealth traded at about 19.3x the floor of its 2026 adjusted EPS guide, and about 18.4x at the $377.76 earnings-day close.
| Measure | At $395.62 (Oct 14 close) | At $377.76 (Oct 13 close) |
|---|---|---|
| Price / 2026 adjusted EPS guide floor ($20.50) | 19.3x | 18.4x |
| Price / 2026 GAAP EPS guide floor ($19.50) | 20.3x | 19.4x |
| Market capitalisation (quoted) | $339.1B | n/a |
| Market capitalisation / total equity ($104.1B) | 3.3x | n/a |
| Annualised dividends paid, as share of quoted market cap | 2.4% | n/a |
| Distance from 52-week high ($461.62) | -14.3% | -18.2% |
All ratios are derived. The guide is "at least", so the multiples are ceilings on a floor of earnings. The quoted market cap of $339.1B implies about 857M shares, while Q3 weighted diluted shares were 902M; I used only the price for the earnings multiples. Annualised dividends are $6,170M x 12 / 9. Total equity includes noncontrolling interests. Prices are from a secondary source and have moved since.
Risks: What Would Break The Thesis
The concern is that earnings quality is lower than the headline and the shrinking book cannot keep supplying margin recovery.
- Reserve release does not repeat. If Q4 has no comparable release, the medical care ratio would move back toward 89% (derived). The release does not say how much of this the Q4 guide of at least $2.20 assumes.
- Commercial cost trend. Zacks says employer plan costs ran above the 11% initial expectation, and Healthcare Dive reports Q3 as the second straight quarter of high commercial spending, with No Surprises Act arbitration payouts near 6% of medical spend in some regions.
- Membership losses. Medicare Advantage lost 840,000 since December and the company expects to lose more than 1 million in 2026 (Healthcare Dive). Lower 2027 star ratings (68% of members in 4 star plans, from 81%) put revenue at risk.
- Optum Health. Revenue fell 9.9% and its adjusted margin was 2.6%. Optum Health's $735M is a third of the company's $2,248M gain in operating earnings, so a slip there matters.
- Leverage. Debt-to-capital moved up to 41.7% against a goal of about 40%, while the company is returning half of its free cash flow to shareholders.
- Guidance is a floor. A Q4 well above $2.20 would be supportive; a Q4 at $2.20 means earnings run at less than half of Q3's rate.
What To Watch Next
- Q4 and the 2027 outlook. Management has said it will give a fuller 2027 outlook before year end. The CFO pointed to the low end of 13% to 16% earnings growth as a reasonable starting point (Zacks).
- Reserve development. Whether Q4 shows another favorable release, and the prior-year comparison for Q3.
- Medical care ratio. Whether it holds near 88% without reserve help, and the size of the commercial cost trend.
- Medicare Advantage. 2027 membership, margin and star rating outcomes.
- Optum Health. Margin on revenue that is falling, and the number of consumers served.
- Debt-to-capital. Whether it falls to about 40% by year end.
- Regulatory costs. Healthcare Dive cites an $11 billion regulatory and cost headwind over three years, and the effect of No Surprises Act arbitration.
Sources And Data Notes
Financial figures come from UnitedHealth Group's Q3 2026 earnings release (Exhibit 99.1 to Form 8-K), reported Oct 13, 2026. Q3 2026 is the three months ended September 30, 2026. I did not read the Form 10-Q or the call transcript. Prices are from Oct 13 and Oct 14 and will have moved.
Primary sources
Secondary sources
- XTB: consensus figures, prior guidance ranges
- Tradingpedia: LSEG consensus, premarket price, regulatory headwind
- HeyGoTrade: Oct 13 and Oct 14 closes, volume, 52-week range, market cap, Zacks and 24/7 Wall St. commentary, CFO 2027 remark
- Healthcare Dive: Medicare Advantage, Medicaid and commercial commentary
Marked, not independently confirmed
- The prior guidance ranges and the consensus figures come from third parties, not the release, which does not state prior guidance.
- The CFO's comment on 2027 and the commercial trend versus 11% come from a news summary of the call.
- Medicare Advantage membership, star rating and margin commentary are from Healthcare Dive, not the filing.
Where sources disagree
- Q3 adjusted EPS consensus: $4.12 (XTB, Zacks) versus $4.14 (LSEG). I used $4.12 for the beat and note both.
- The stock on earnings day: Tradingpedia shows a premarket gain of 2.2%, XTB says nearly 3%, and HeyGoTrade's data show a 0.23% decline at the close with the rally coming the next session.
- The release says seniors contracted by 935,000 since year end, while the table shows Medicare Advantage down 840,000 and Medicaid down 685,000.
- The quoted market cap of $339.1B implies fewer shares (about 857M) than the 902M Q3 diluted weighted average.
- The release labels the $610M reserve development as "prior period" and also as relating to 2026 dates of service.
Left out
- Segment medical care ratios, which the release does not give, and the amount of loss contract reserves excluded from the full-year adjusted guide.
- An Oct 28 or later price, which I could not confirm.
Derived figures are my arithmetic from the release and are marked (d), "derived" or "my arithmetic".

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Related Research
 DHR
Danaher (DHR): Core Sales Up 3% And Adjusted EPS Up 11.5%, But A Tax Swing Was 81% Of The Net Earnings Gain
 ISRG
Intuitive Surgical (ISRG): Non-GAAP EPS Up 25%, GAAP EPS Down 24%, And A $450M Settlement Explains Two-Thirds Of The Gap
 MRK
Merck (MRK): Revenue Up 5%, But $550M Of Purchase Timing Was About Two-Thirds Of The Increase
Latest earnings releases: UNH
— earningsrelease3q26unh 1 UnitedHealth Group Reports Third Quarter 2026 Results
Discussion
Be the first to comment.