
Investment Thesis
Merck reported third-quarter revenue of $18.1B, up 5%, but the CFO also said purchase timing added about $550M to U.S. sales in the quarter, and that part of it will unwind in the fourth quarter and 2027. Without that benefit, revenue growth was roughly 2% (d). Keytruda is still about 47% of revenue, operating expenses grew 12%, and the full-year EPS guide leaves little room for the other quarters.
- Revenue. Total revenue was $18.1B, up 5% (4% excluding FX). The Keytruda family, including Keytruda QLEX, was $8.6B, up 6%.
- Purchase timing. About $550M of U.S. purchases benefited Q3: $200M for Keytruda, $50M for Winrevair and $300M for vaccines. Keytruda's $200M and Winrevair's $50M unwind in Q4. Of the vaccine amount, $50M unwinds in Q4 and $250M in 2027.
- Underlying growth. The $550M equals about 64% of the roughly $0.86B revenue increase (d), leaving growth of about 1.8% (d). For Keytruda, $200M is about 41% of its increase, leaving about 3.5% (d).
- Growth products. Winrevair was $694M (+94%), Welireg $370M (+58%), Gardasil $2.0B (+14%), and Ohtuvayre $184M. Animal health rose 3%.
- Costs. Non-GAAP operating expenses rose 12% to $7.4B, more than twice revenue growth. Non-GAAP gross margin fell slightly to 81.4%. A $400M upfront business development charge compares with $300M a year earlier.
- EPS. Non-GAAP EPS was $2.49, including a $0.12 per share charge for the license deal. The full-year guide is $2.77 to $2.82, so the other three quarters together would earn about $0.31 (d).
- Guidance. 2026 revenue is guided to $66.8B to $67.3B (+3% to 4%), gross margin about 81%, operating expenses $42.4B to $42.9B, tax rate 32% to 33%, buybacks about $3B.
- This article contains no price target or rating. Every figure comes from the executives' spoken remarks on the Q3 call or a named source, and anything I calculated is marked (d).
Bottom line. Merck's Q3 looks like steady 5% growth, but the quality is lower than the headline: roughly two-thirds came from purchase timing that management says will unwind. Underlying growth of about 2%, a Keytruda franchise at 47% of revenue and operating expenses growing 12% mean the investor case depends on Winrevair, Welireg and the 2027 expense outlook.
Source: Merck Q3 2026 earnings call transcript, Motley Fool, Oct 29, 2026.
Q3 2026 At A Glance
| Metric (Q3 2026) | Result | Growth |
|---|---|---|
| Total revenue | $18.1B | +5% (+4% ex-FX) |
| Keytruda family (incl. QLEX) | $8.6B | +6% |
| Keytruda QLEX | $830M | n/a |
| Gardasil | $2.0B | +14% (U.S. +18%, international +6%) |
| Winrevair | $694M | +94% |
| Welireg | $370M | +58% |
| Capvaxive | $263M | +7% ex-FX (U.S. -13%) |
| Winflonzia | $187M | n/a |
| Ohtuvayre | $184M | n/a |
| Animal health | n/a | +3% |
| Non-GAAP gross margin | 81.4% | slightly lower |
| Non-GAAP operating expenses | $7.4B | +12% |
| Non-GAAP tax rate | 10.9% | n/a |
| Non-GAAP EPS | $2.49 | includes $0.12 license charge |
Source: Merck Q3 2026 call transcript.
What The Market Believes vs. What The Data Actually Shows
| Belief | What the call shows |
|---|---|
| Merck is growing 5% | About $550M of U.S. purchase timing contributed; growth without it is about 1.8% (d). |
| Keytruda is steady | Keytruda grew 6%, or about 3.5% without a $200M purchase benefit (d). |
| New products will replace Keytruda | Winrevair, Welireg, Ohtuvayre and Winflonzia together were about $1.4B (d), against $8.6B for Keytruda. |
| Costs are controlled | Non-GAAP operating expenses grew 12%, against 5% revenue growth; 2027 underlying growth is guided to mid-to-high single digits. |
| The guide is conservative | The EPS guide midpoint of $2.795 leaves about $0.31 for the other three quarters (d). |
The call gave no consensus; prices are in the Valuation Snapshot.
A 5% growth rate would normally support the premium valuation of a large-cap pharmaceutical. The timing adjustment matters because Merck's own call quantified it, which gives investors a rare chance to separate reported from underlying growth.
Forensic #1: $550M Of Purchase Timing Was Most Of The Increase
| Item | Amount |
|---|---|
| Q3 2026 revenue | $18.1B |
| Prior-year revenue (d, from +5%) | about $17.24B |
| Increase (d) | about $0.86B |
| U.S. purchase timing benefit | about $550M |
| Timing as share of increase (d) | about 64% |
| Growth excluding timing (d) | about 1.8% |
| Keytruda timing / Keytruda increase (d) | $200M / about $0.49B = 41% |
| Keytruda growth excluding timing (d) | about 3.5% |
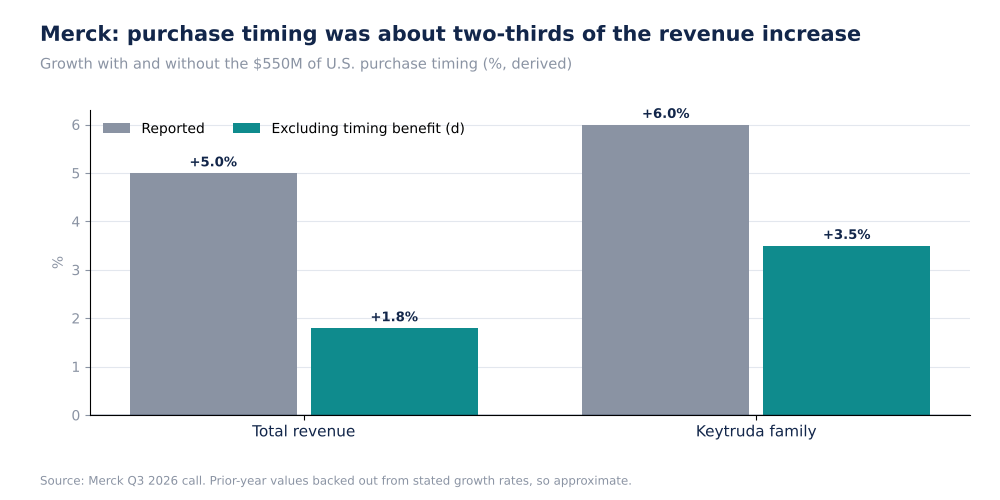
Merck Q3 2026 Revenue Growth With And Without U.S. Purchase Timing, Derived (Self-Made)
Of the $550M, about $300M is expected to unwind in Q4 ($200M Keytruda, $50M Winrevair, $50M vaccines) and $250M of vaccine purchases in 2027 (d). A CDC purchase of about $250M in 2026 also unwinds in 2027.
Why it matters. About $300M gives back in Q4, so reported growth next quarter will look weaker, and the vaccine amount reverses again in 2027 along with a CDC purchase of about $250M. An investor modelling 2027 should treat these as a headwind on a high base, not as underlying demand.
Source: Merck Q3 2026 call transcript. Derived values use rounded growth rates and are approximate.
Forensic #2: Keytruda Is 47% Of Revenue
| Product | Q3 2026 | Share of revenue (d) |
|---|---|---|
| Keytruda family | $8.6B | 47.5% |
| Gardasil | $2.0B | 11.0% |
| Winrevair | $694M | 3.8% |
| Welireg | $370M | 2.0% |
| All other (d) | $6.4B | 35.6% |
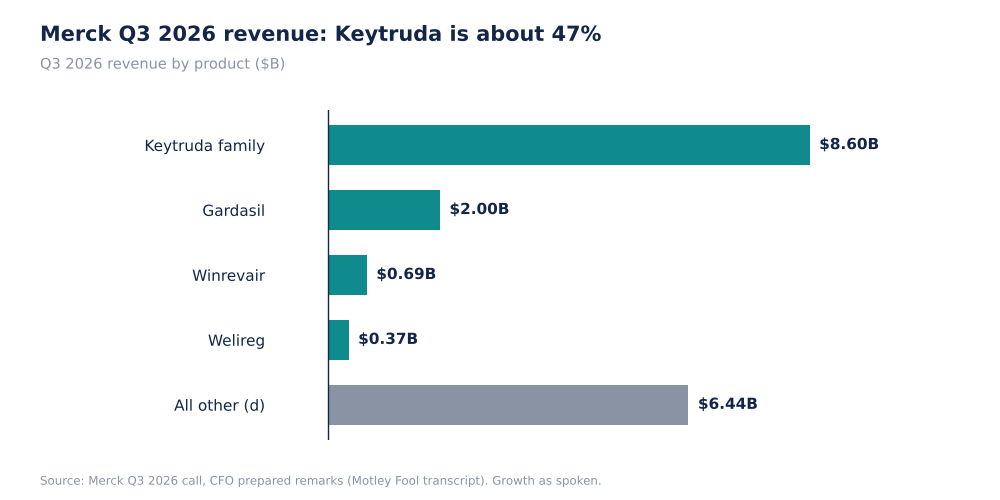
Merck Q3 2026 Revenue By Product, $B (Self-Made)
Winrevair grew 94% but is under 4% of revenue. About 1.6 thousand new U.S. patients started on it, and about 30% were not on a prostacyclin. Welireg's growth is spoken as 58% at $370M; the page summary lists $307M, which I treat as a transcription difference.
Why it matters. Keytruda is the main swing factor, and its growth excluding timing, about 3.5% (d), is slower than the company total. The fast growers are small: Winrevair, Welireg, Ohtuvayre and Winflonzia together are about $1.4B, or 8% of revenue (d). Their dollar growth needs to be several times larger before it offsets any slowdown in Keytruda.
Source: Merck Q3 2026 call transcript.
Forensic #3: Operating Expenses Outgrew Revenue And A Licence Charge Hit EPS
| Item | Q3 2026 | Comparison |
|---|---|---|
| Non-GAAP operating expenses | $7.4B | +12%; about $6.6B a year ago (d) |
| Non-GAAP gross margin | 81.4% | slightly lower |
| Business development charge | $400M upfront | $300M a year earlier |
| Charge per share | $0.12 | included in $2.49 EPS |
| Other expense | $420M | n/a |
| Tax rate | 10.9% | 2026 guide 32% to 33% |
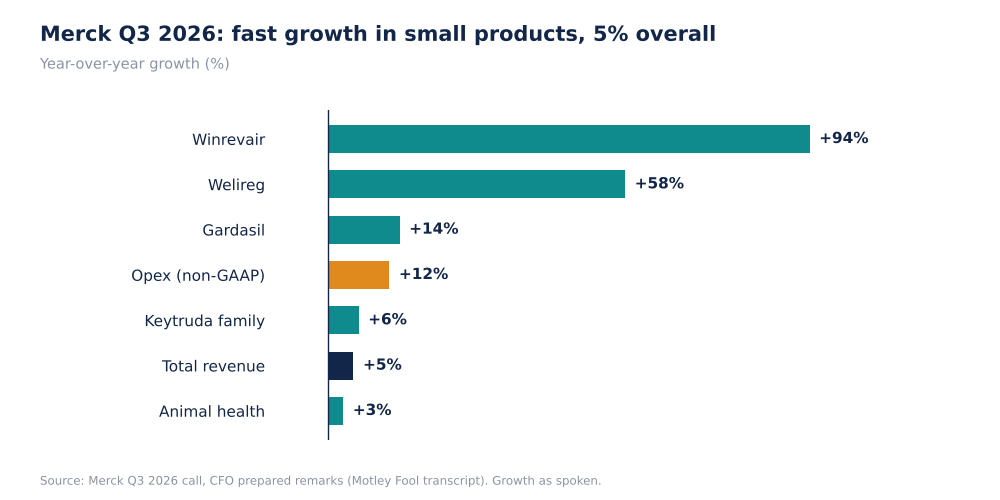
Merck Q3 2026 Growth By Product And Operating Expenses (Self-Made)
The transcript names the licence agreement inconsistently (it renders the partner as "Ceybrion", and other sources call it "SciBrunch"), so I do not name it. The 10.9% Q3 tax rate contrasts with the 32% to 33% full-year guide, a gap the spoken remarks do not explain.
Why it matters. When operating expenses grow 12% on 5% revenue growth, margins fall unless gross margin rises, and gross margin slipped to 81.4%. Business development charges of $400M this year and $300M last year suggest that licence deals are a regular cost of keeping the pipeline full, so investors should not treat them as pure one-offs.
Source: Merck Q3 2026 call transcript.
Forensic #4: The Full-Year EPS Guide Leaves About $0.31 For Three Quarters
| Item | Figure |
|---|---|
| Q3 non-GAAP EPS | $2.49 |
| 2026 EPS guide | $2.77 to $2.82 (includes about $0.15 FX benefit and the licence charge) |
| Guide midpoint (d) | $2.795 |
| Q3 as share of midpoint (d) | 89% |
| Implied EPS for the other three quarters combined (d) | about $0.31 |
| 2026 revenue guide | $66.8B to $67.3B |
| 2026 shares outstanding | about 2.48B |
I did not read Merck's first- and second-quarter results, so I cannot say what large charges sit in them or in Q4. The arithmetic means either the other quarters carried charges, or Q4 will, and a reader should check the filing before drawing a conclusion.
Why it matters. A full-year guide of $2.77 to $2.82 sits well below four times Q3 EPS of $2.49, so quarters outside Q3 carry charges, and the guide is a poor basis for a P/E. The investor's task is to find EPS excluding charges, which the call did not provide, before using a multiple.
Source: Merck Q3 2026 call transcript.
Valuation Snapshot
TradingView shows Merck at $149.52, up 2.2% on the day and 41.7% year to date, about 4.7% below its Aug 25, 2026 high of $156.92. Market cap is about $368.9B. The page lists Q3 EPS of $2.49 against an estimate of $2.09, with no source or date for the estimate.
| Measure | Figure |
|---|---|
| Share price (TradingView) | $149.52 |
| Market cap (TradingView) | about $368.9B |
| Quarterly dividend / yield (TradingView) | $0.85 / about 2.3% |
| Price / 2026 EPS guide midpoint of $2.795 (d) | about 53.5x |
| Price / annualised Q3 EPS of $9.96 (d) | about 15.0x |
| Market cap / 2026 revenue guide low end of $66.8B (d) | about 5.5x |
| Below the Aug 25 all-time high (d) | about 4.7% |
The two P/E figures differ by a factor of more than three because the full-year guide includes large charges and Q3 did not. The price is near its high while underlying revenue growth, excluding purchase timing, was about 1.8% (d), so the market is looking past the quarter.
What has to be true. Near its August high and about 42% up year to date, the stock prices in more than the roughly 2% underlying growth of Q3. The support is the 2.3% dividend yield and the growth of Winrevair and Welireg. The pressure is Keytruda concentration and the 2027 unwind.
Risks: What Would Break The Thesis
- Timing unwinds. About $300M reverses in Q4 and $250M in 2027 (d).
- Keytruda concentration. 47% of revenue in one franchise.
- Costs. Operating expenses grew 12%; 2027 underlying growth is guided to mid-to-high single digits.
- Vaccines. Capvaxive U.S. sales fell 13%.
- Data limits. The transcript is machine-generated and the release was not read.
Most of the risks are known and dated: the Q4 unwind, the 2027 unwind and expense growth. The unknown risk is how fast new products replace Keytruda.
What To Watch Next
- Q4 revenue with about $300M of timing unwinding.
- Keytruda growth excluding timing against 3.5% (d).
- Winrevair against $694M.
- The EPS bridge from $2.49 to the full-year guide.
- 2027 operating expense growth.

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Related Research
 DHR
Danaher (DHR): Core Sales Up 3% And Adjusted EPS Up 11.5%, But A Tax Swing Was 81% Of The Net Earnings Gain
 ISRG
Intuitive Surgical (ISRG): Non-GAAP EPS Up 25%, GAAP EPS Down 24%, And A $450M Settlement Explains Two-Thirds Of The Gap
 LLY
Eli Lilly (LLY): Two Drugs Drove 88% Of Growth, EPS Hit By $4.57 R&D
Latest earnings releases: MRK
— Merck & Co., Inc., Rahway, N.J., USA Announces Third-Quarter 2026 Financial Results
— Merck & Co., Inc., Rahway, N.J., USA Announces Second-Quarter 2026 Financial Results
Discussion
Be the first to comment.