
Investment Thesis
Eli Lilly grew revenue 39% to $24.4B and raised its 2026 revenue guide to $91B to $92B, but two drugs supply 88% of the growth, realised price fell 15%, and $4.57 per share of acquired R&D cut non-GAAP EPS growth to 7%.
- Earnings. Revenue was $24,397M (+39%) against $22.42B expected. Non-GAAP EPS was $7.48 (+7%) against $5.60 expected (Investing.com). Reported EPS was $7.22 (+16%).
- Concentration. Mounjaro ($10,723M) and Zepbound ($5,352M) together were $16,075M, 66% of revenue, and added $5,972M of the $6,796M revenue increase, or 88% (derived). All other products combined grew 11% (derived).
- Price. Volume rose 53% and realised price fell 15%. Outside the U.S. volume rose 76% and price fell 29%. About $900M of Q3 revenue came from one-time benefits, mainly $410M of Jardiance milestones and favourable rebate and discount adjustments.
- Acquired R&D. Acquired in-process R&D was $4,181M, or $4.57 per share, against $656M and $0.71. Adding it back, non-GAAP EPS would be $12.05 against $7.73, up 56% (derived).
- Guidance. Non-GAAP EPS guidance moved to $35 to $36 from $35.50 to $36.50, a $0.50 cut at the midpoint, even though revenue guidance rose $5.5B. The release attributes this to the $4.57 charge offsetting a $4.07 underlying raise.
- Cash. Nine-month operating cash flow doubled to $27.4B and free cash flow reached $19.0B (derived). Acquisitions and purchased R&D took $18.2B of it, 96% (derived).
- Balance sheet. Inventories rose 32% and other intangibles rose 177% since December. Goodwill and intangibles are now 69% of equity, and tangible equity fell 13% (derived).
- Stock. It closed at $1,288.30 before the report and traded 6.5% higher at $1,371.60 premarket on Oct 29 (Investing.com). At the pre-report price it was about 36x the guided EPS midpoint (derived).
- This article contains no price target or rating. Every figure comes from Lilly's filings or a named source, and anything I calculated is marked.
Sources: Lilly Form 10-Q for the quarter ended Sept 30, 2026; Lilly Q3 2026 results release, as published by BioSpace.
Q3 2026 At A Glance
Revenue grew 39% and net income grew 16%, because acquired R&D took $4.2B out of the quarter.
| Metric (quarter ended Sept 30) | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Total revenue | $24,397M | $17,601M | +39% (volume +53%, price -15%) |
| U.S. revenue | $15,136M | $11,300M | +34% (volume +41%, price -7%) |
| Outside U.S. revenue | $9,261M | $6,301M | +47% (volume +76%, price -29%) |
| Gross margin (reported / non-GAAP) | 83.9% / 84.4% | 82.9% / 83.6% | +1.0 / +0.8 pts |
| Research and development | $4,247M | $3,466M | +23% (d) |
| Marketing, selling and administrative | $3,125M | $2,741M | +14% (d) |
| Acquired IPR&D | $4,181M | $656M | 6.4x (d) |
| Income before taxes | $8,406M | $7,233M | +16% (d) |
| Effective tax rate (reported / non-GAAP) | 23.3% / 24.0% | 22.8% / 17.7% | n/m |
| Net income (reported) | $6,451M | $5,583M | +16% (d) |
| Diluted EPS (reported) | $7.22 | $6.21 | +16% |
| Non-GAAP EPS | $7.48 | $7.02 | +7% |
| Weighted diluted shares | 893.4M | 898.8M | -0.6% (d) |
(d) = derived. Both Q3 2026 EPS figures include $4.57 of acquired IPR&D per share (Q3 2025: $0.71). Sources: Lilly Form 10-Q; Lilly Q3 2026 results release.
What The Market Believes vs. What The Data Actually Shows
Lilly beat revenue and EPS estimates and raised revenue guidance, and the stock rose 6.5% premarket, but the EPS guide fell and the price per unit keeps dropping.
| Item | Result or guide | Comparison |
|---|---|---|
| Revenue | $24.4B | $22.42B expected (Investing.com), +8.8% |
| Non-GAAP EPS | $7.48 | $5.60 expected (Investing.com), +$1.88 |
| 2026 revenue | $91B to $92B | Raised from $85B to $87B; midpoint +$5.5B |
| 2026 non-GAAP EPS | $35.00 to $36.00 | Prior $35.50 to $36.50; midpoint -$0.50 |
| 2026 performance margin (non-GAAP) | 52.0% to 52.5% | Raised from 49.0% to 50.5% |
| 2026 non-GAAP tax rate | 19% to 20% | Raised from 18% to 19% |
| Share count in guidance | About 894M | Guide excludes acquired IPR&D after Sept 30 |
Price reaction: Investing.com reports Lilly rose 6.47% to $1,371.60 in premarket trading on Oct 29, from a prior close of $1,288.30. I could not confirm the closing price for Oct 29 or any later date, so the valuation below uses both quotes.
Whether the EPS estimate of $5.60 was set before or after the $4.57 charge matters. Guidance excludes IPR&D that has not yet been incurred, so analysts usually cannot model it, and the beat is not a clean measure of operations. On the call, management said about $2B of 2026 one-time items, including milestones and rebate and discount estimate changes, will not recur (call summary).
Sources: Lilly Q3 2026 results release; Investing.com call transcript summary.
Forensic #1: Two Drugs Are 66% Of Revenue And 88% Of Growth
Mounjaro and Zepbound added $5,972M of the $6,796M increase in quarterly revenue.
| Revenue bridge | Q3 2026 vs Q3 2025 |
|---|---|
| Q3 2025 revenue | $17,601M |
| Mounjaro (+65%, $6,515M to $10,723M) | +$4,208M (d) |
| Zepbound (+49%, $3,588M to $5,352M) | +$1,764M (d) |
| All other products and revenue | +$824M (d) |
| Q3 2026 revenue | $24,397M |
(d) = derived. Source: Lilly Form 10-Q.
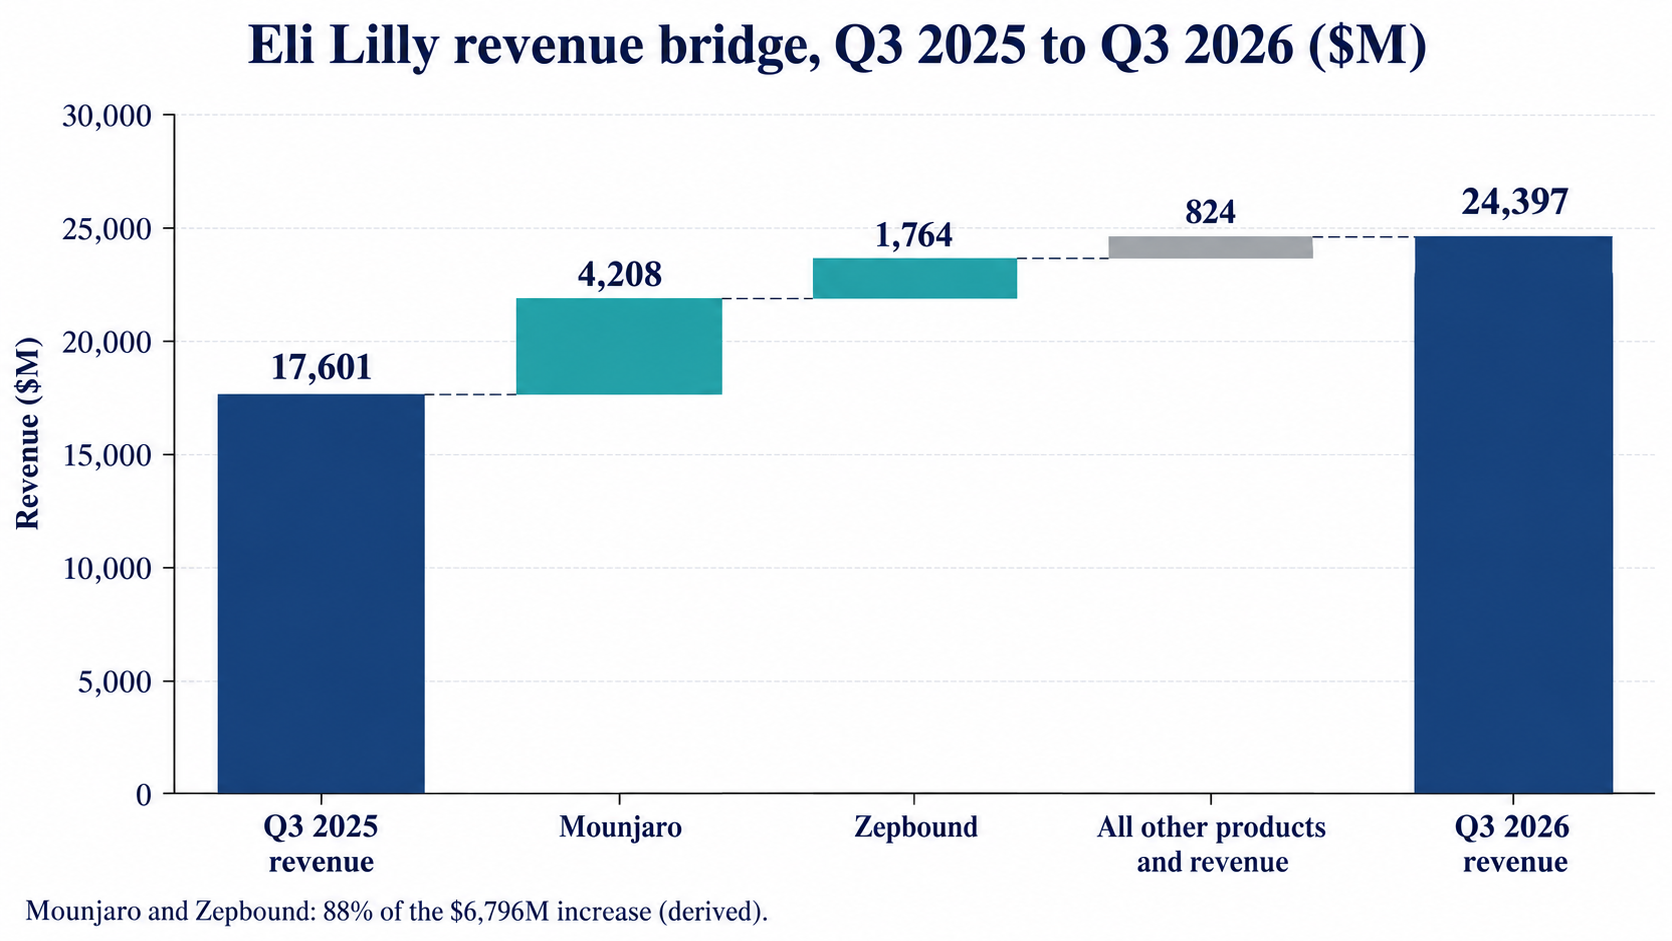
Q3 2026 Revenue Bridge From Q3 2025, By Product Group, $M (Self-Made)
The rest of the portfolio is mixed. Trulicity fell 14% to $904M, Taltz fell 5% to $856M, and Verzenio rose 3% to $1,511M. Jardiance rose 65% to $1,578M, and the release cites $410M of Jardiance milestones in the roughly $900M of Q3 one-time benefits. The release extract I read does not say which revenue line the milestones were booked in, so I did not adjust the product figures. Neuroscience, immunology and oncology grew 41%, 5% and 8% (derived from the 10-Q totals).
Mounjaro is now more international than domestic: $5,725M outside the U.S. against $4,998M in the U.S. Zepbound is almost all U.S. ($5,267M of $5,352M). Newer products are small so far: the release lists Foundayo at $184M, Jaypirca at $228M, Ebglyss at $202M and Kisunla at $193M in Q3.
Sources: Lilly Form 10-Q; Lilly Q3 2026 results release.
Forensic #2: Volume Rose 53%, Price Fell 15%, And $900M Will Not Recur
Growth is coming from selling many more doses at much lower prices.
| Q3 2026 vs Q3 2025 | Volume | Realised price | Revenue growth |
|---|---|---|---|
| Worldwide | +53% | -15% | +39% |
| United States | +41% | -7% | +34% |
| Outside U.S. | +76% | -29% | +47% |
Source: Lilly Q3 2026 results release. Currency effects were not stated in the extract I read, and the components are additive, not multiplicative.
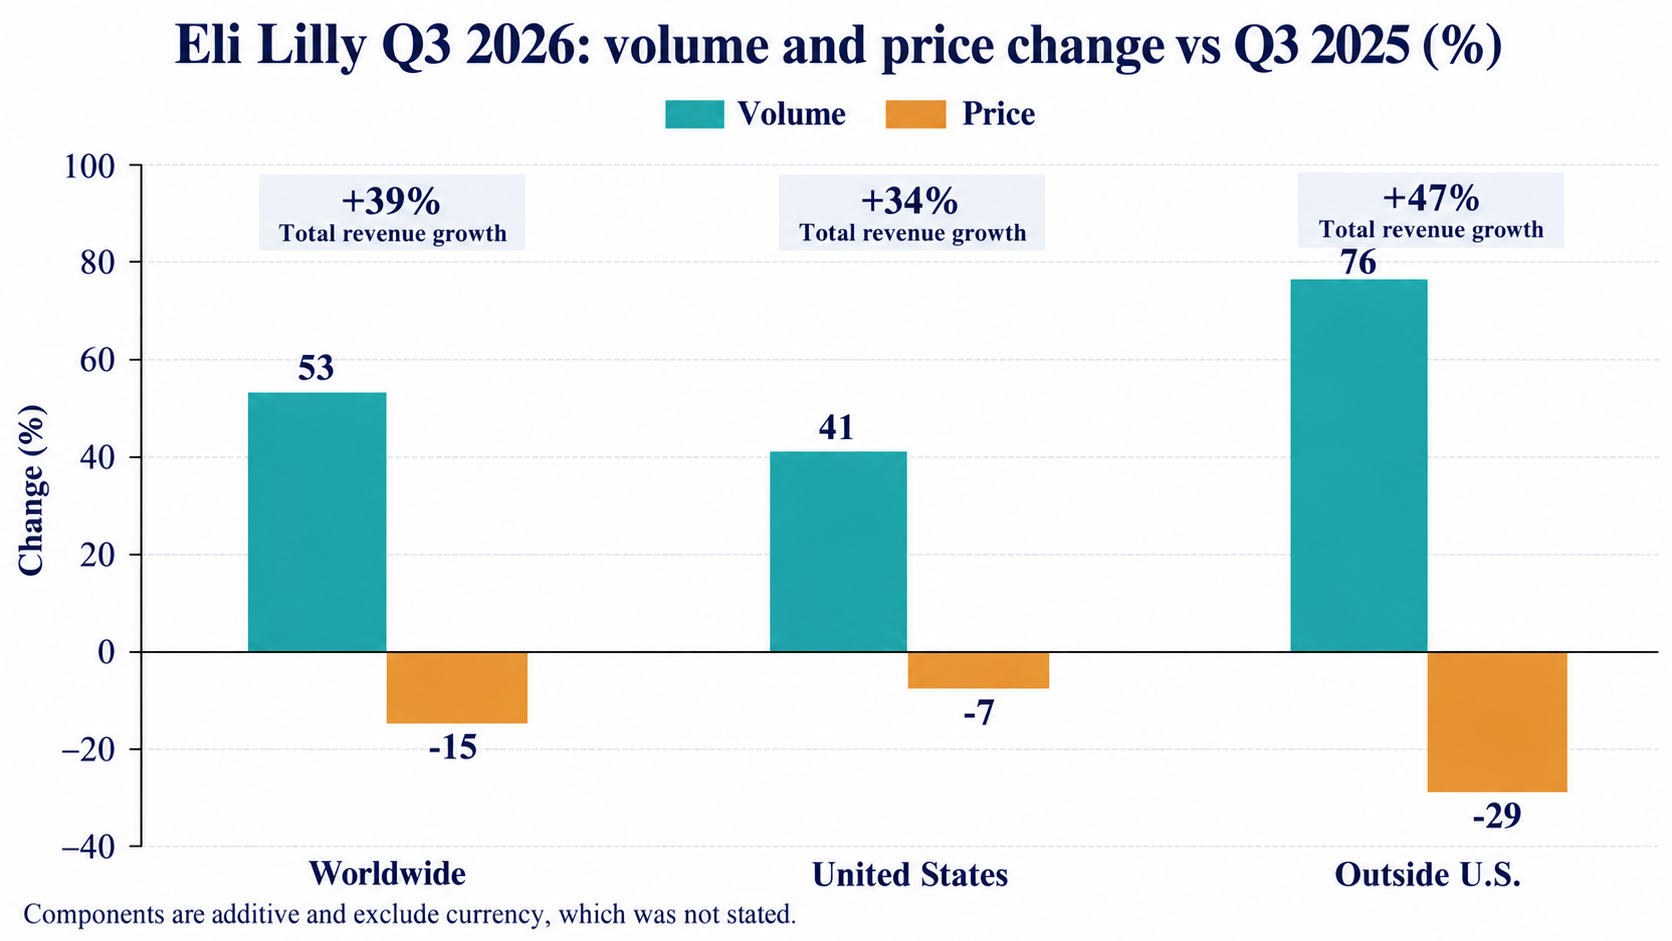
Q3 2026 Volume And Realised Price Change vs Q3 2025, By Region (Self-Made)
The U.S. price decline of 7% includes a favourable rebate and discount adjustment; the call summary says excluding it the U.S. price fell 10%. The 10-Q says adjustments to U.S. revenue from prior-period sales returns, rebates and discounts were 2% of U.S. revenue in 2026 against under 1% in 2025. The liability for sales rebates and discounts grew to $24,170M from $17,382M at December (+39%), larger than accounts receivable of $22,089M (derived).
About $900M of Q3 revenue was one-time, 3.7% of the total (derived). If Q3 2025 had no comparable items, which the release does not say, underlying growth was about 33.5% (derived). The guide for the year implies Q4 revenue of $23,830M to $24,830M (derived from $91B to $92B less nine-month revenue of $67,170M), which is 2.3% below to 1.8% above Q3. Management expects net realised price to stay a headwind in 2027, offset by volume growth, and to give full 2027 guidance in January (call summary).
Sources: Lilly Q3 2026 results release; Lilly Form 10-Q; Investing.com call transcript summary.
Forensic #3: $4.57 Per Share Of Acquired R&D Hides A 56% Underlying EPS Gain
Lilly is buying its pipeline, and the cost runs through earnings.
| Per share | Q3 2026 | Q3 2025 | Change |
|---|---|---|---|
| Reported EPS | $7.22 | $6.21 | +16% |
| Amortization of intangibles | +$0.11 | +$0.11 | |
| Asset impairment, restructuring and other | +$0.18 | +$0.36 | |
| Net gains on equity securities | -$0.04 | -$0.04 | |
| U.S. tax law change | none | +$0.39 | |
| Acquired IPR&D (included, not removed) | $4.57 | $0.71 | |
| Non-GAAP EPS | $7.48 | $7.02 | +7% |
| Non-GAAP EPS before acquired IPR&D | $12.05 | $7.73 | +56% (d) |
(d) = derived: non-GAAP EPS plus acquired IPR&D per share. Lilly's non-GAAP measure does not remove acquired IPR&D. Source: Lilly Q3 2026 results release.
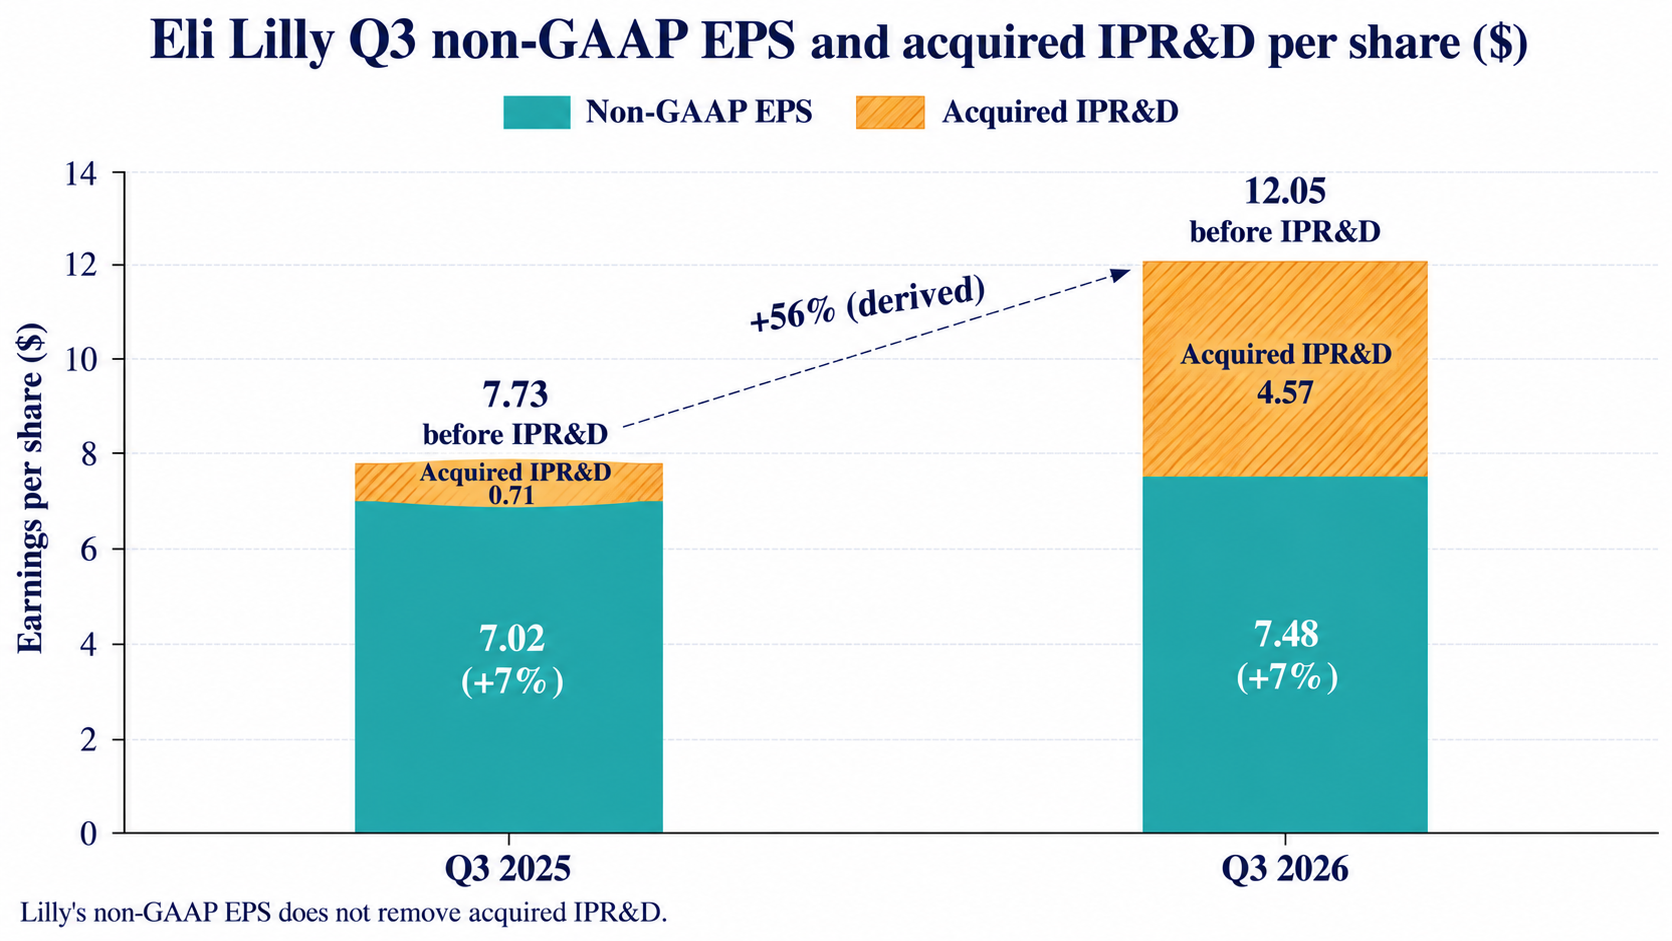
Q3 Non-GAAP EPS And The Acquired IPR&D Charge Per Share, 2025 vs 2026 (Self-Made)
Acquired IPR&D was $4,181M in Q3 and $7,541M for nine months, against $2,381M a year ago. The 10-Q names the Q3 deals: AtaiBeckley at $2,610M and Curevo at $954M, together $3,564M or 85% of the quarter's charge (derived). Earlier in 2026 it lists Orna at $1,233M and Ajax at $909M. It also reports the business combinations of Kelonia, Centessa and Ventyx, and a subsequent-event acquisition of Merida Biosciences in October for up to $2.9B including milestones. The press release's own wording on whether Merida had completed is inconsistent.
The guidance arithmetic follows. Underlying EPS guidance rose $4.07 at the midpoint, the $4.57 charge more than offset it, and the guide fell $0.50. Because guidance excludes IPR&D incurred after Sept 30, any further deals in Q4 would lower EPS again. The October Merida deal could be one, but I did not see how Lilly will account for it. The non-GAAP tax rate guide rose to 19% to 20% from 18% to 19%, and the 10-Q says the 2026 tax rates were driven by the unfavourable tax effect of nondeductible IPR&D. The Q3 non-GAAP tax rate was 24.0% against 17.7%.
Sources: Lilly Q3 2026 results release; Lilly Form 10-Q.
Forensic #4: Free Cash Flow Doubled, And 96% Of It Went To Acquisitions
Lilly's cash generation is large, and so is the amount it is putting back into assets.
| Nine months ended Sept 30 | 2026 | 2025 | Change |
|---|---|---|---|
| Net cash from operating activities | $27,420M | $13,588M | +102% (d) |
| Purchases of property and equipment | $8,437M | $5,294M | +59% (d) |
| Operating cash flow minus capex | $18,983M | $8,294M | +129% (d) |
| Cash paid for acquisitions, net | $10,692M | $549M | 19x (d) |
| Purchases of in-process R&D | $7,548M | $2,584M | 2.9x (d) |
| Dividends paid | $4,635M | $4,039M | +15% (d) |
| Share repurchases | $4,334M | $2,600M | +67% (d) |
| Net debt issued (proceeds less repayments) | $7,318M | $12,389M | n/m (d) |
(d) = derived. Operating cash flow minus capex is my measure, not a company figure. Source: Lilly Form 10-Q.
Acquisitions and purchased R&D together were $18,240M, 96% of the $18,983M (derived). Adding dividends and buybacks of $8,969M brings uses to $27,209M, $8,226M more than free cash flow, which was funded by $7,318M of net new debt and a $2,383M fall in cash (derived).
| Balance sheet | Sep 30, 2026 | Dec 31, 2025 | Change |
|---|---|---|---|
| Cash and cash equivalents | $4,885M | $7,268M | -33% (d) |
| Accounts receivable | $22,089M | $17,760M | +24% (d) |
| Inventories | $18,194M | $13,744M | +32% (d) |
| Property, plant and equipment, net | $32,188M | $24,675M | +30% (d) |
| Goodwill | $9,874M | $5,898M | +67% (d) |
| Other intangibles, net | $18,084M | $6,521M | +177% (d) |
| Sales rebates and discounts liability | $24,170M | $17,382M | +39% (d) |
| Total debt (carrying amount) | $49,503M | $42,503M | +16% (d) |
| Total equity | $40,271M | $26,535M | +52% (d) |
(d) = derived. Source: Lilly Form 10-Q.
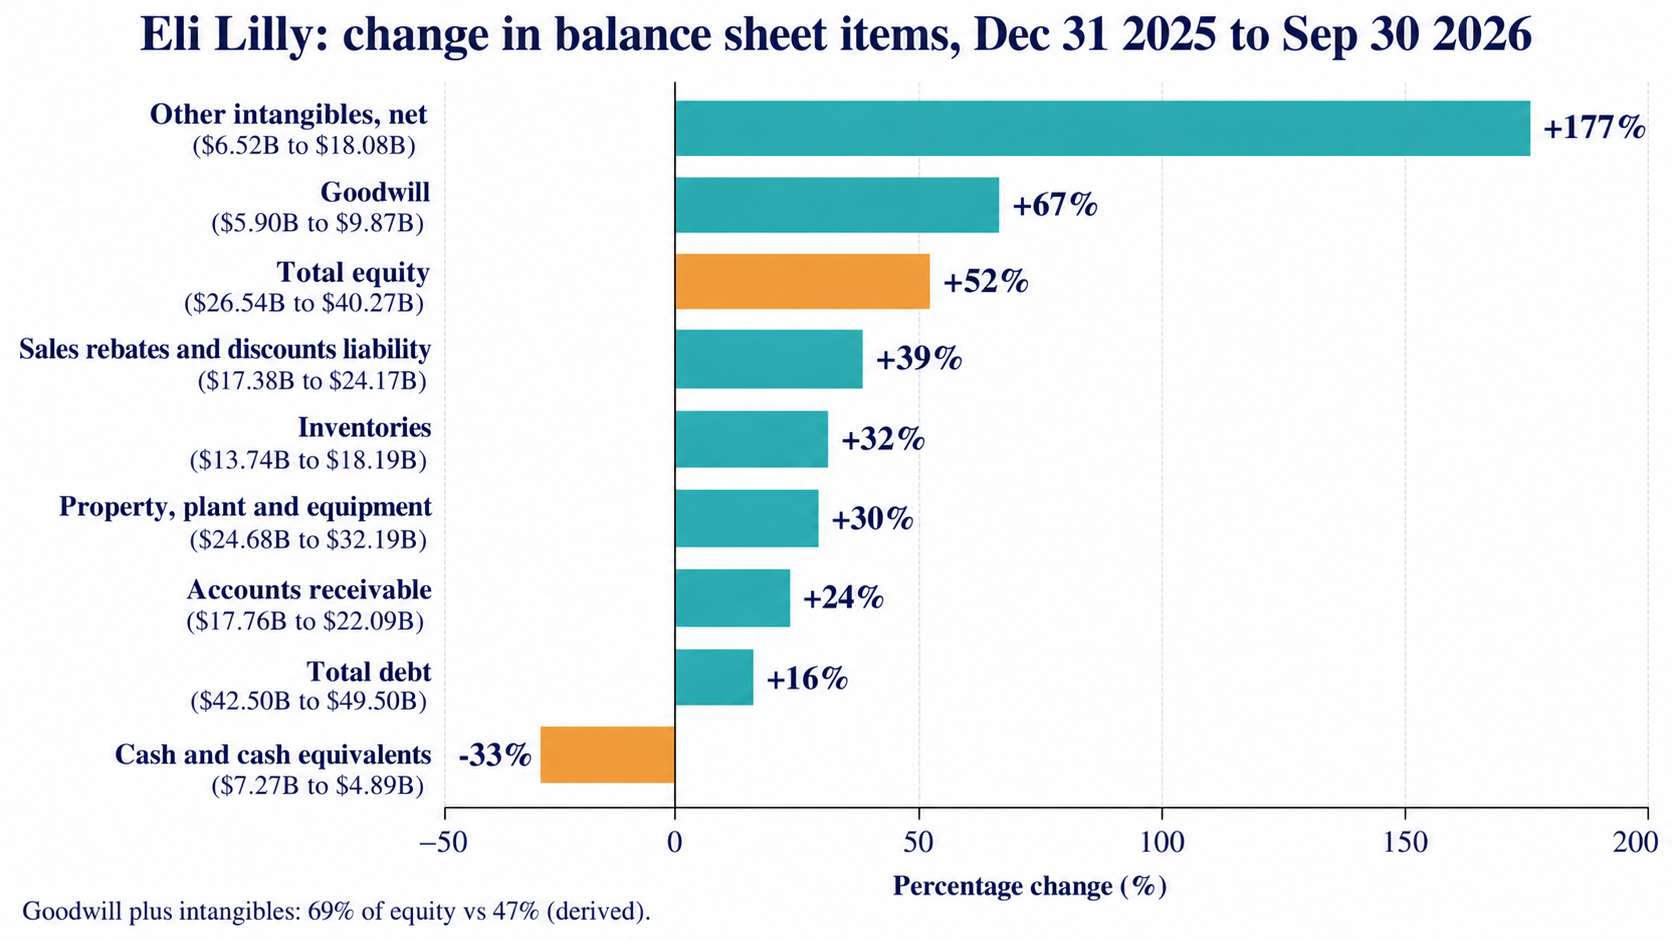
Eli Lilly Balance Sheet Changes From Dec 31, 2025 To Sep 30, 2026 (Self-Made)
Goodwill and intangibles together grew to $27,958M from $12,419M and are 69% of equity, up from 47% (derived). Equity minus goodwill and intangibles fell 13% to $12,313M (derived), because the acquisitions added more intangibles than equity grew. Contingent consideration liabilities rose to $2,888M from $251M. Debt less cash rose 27% to about $44.6B (derived, excluding $4,013M of noncurrent investments). Work in process is $10,688M, 59% of inventories (derived). Lilly issued $9,000M of notes in May at rates from 4.150% to 5.700%, and its two credit facilities, $6.0B and $4.0B, are undrawn.
The company is also building capacity: groundbreakings on a facility in Houston ($6.5B) and one in Richmond ($5B), per the call summary. Capex of $8,437M in nine months already reflects part of this.
Sources: Lilly Form 10-Q; Investing.com call transcript summary.
Valuation Snapshot
At $1,288.30, Lilly traded at about 36x the midpoint of its 2026 non-GAAP EPS guide, and about 39x at the premarket price.
| Measure | At $1,288.30 (prior close) | At $1,371.60 (Oct 29 premarket) |
|---|---|---|
| Market capitalisation (893.4M diluted shares) | $1.15T | $1.23T |
| Price / 2026 non-GAAP EPS guide midpoint ($35.50) | 36.3x | 38.6x |
| Market capitalisation / 2026 revenue guide midpoint ($91.5B) | 12.6x | 13.4x |
| Annualised Q3 dividend ($1.73 x 4) yield | 0.5% | 0.5% |
| Dividend as share of guided non-GAAP EPS midpoint | 19% | 19% |
All ratios are derived. The EPS guide includes acquired IPR&D incurred through Sept 30 (including $4.57 in Q3), so the multiple is higher than it would be on EPS before those charges; the release does not give the nine-month IPR&D per share on a non-GAAP basis. The 10-Q cover shows 940,745,031 shares outstanding as of Oct 26, 2026, which does not reconcile with the 893.4M weighted diluted shares, and I used the weighted figure that matches the guidance share count of about 894M. Prices are from a secondary source and have moved.
Risks: What Would Break The Thesis
The concern is dependence on two drugs whose price keeps falling, and rising spending on acquired assets.
- Price erosion accelerates. Outside the U.S., price fell 29% in Q3. If U.S. price falls as the Medicare programme and other channels scale, volume has to keep growing faster.
- One-time items. About $900M of Q3 revenue and about $2B of 2026 revenue will not recur (call summary). Q4 implied revenue is flat on Q3.
- Concentration. Mounjaro and Zepbound are 66% of revenue. Competition, supply or a safety issue in the class would reach the whole group.
- Deal spending. Acquired IPR&D rose to $7.5B in nine months, and any further deals reduce EPS under Lilly's accounting while guidance excludes them.
- Balance sheet. Intangibles and goodwill are 69% of equity and contingent consideration is $2.9B. Impairments, such as the partial intangible impairment the 10-Q mentions, would reduce equity.
- Working capital. Inventories rose 32% and the rebate liability exceeds receivables. A change in payer mix would show in the rebate line first.
- Valuation. At about 36x to 39x guided EPS the stock already prices continued growth.
What To Watch Next
- Q4 results and 2027 guidance. Management said it will provide 2027 guidance on the Q4 call in January, with expectations for sustained volume growth, a full year of the Medicare GLP-1 Bridge programme and the launch of Foundayo in type 2 diabetes (call summary).
- Realised price. The split between volume and price, especially outside the U.S., and the size of rebate and discount adjustments.
- Medicare Bridge programme. It started July 1, and the call summary says more than half a million people had filled a Lilly prescription through it. It is expected to move into the Part D benefit for 2028.
- Foundayo. A U.S. type 2 diabetes regulatory decision expected in Q4 and sales above the $184M in Q3 (call summary).
- Pipeline. The Phase 3 start for eloralintide plus tirzepatide in Q4, and retatrutide data after the positive head-to-head result against Ozempic in type 2 diabetes.
- Acquired R&D. The accounting for Merida Biosciences and any further deals.
- Balance sheet. Inventory, the rebate liability and debt as new plants come online.
Sources And Data Notes
Financial statement figures come from Eli Lilly's Form 10-Q for the quarter ended September 30, 2026, and its Q3 2026 results release, which I read as published by BioSpace. I could not open the original 8-K on the SEC website, which returned an error. The 10-Q text I read cuts off in Note 8, so Note 9 and later, including litigation, are not covered. Prices are from Oct 28 and Oct 29 and will have moved.
Primary sources
- Eli Lilly Form 10-Q for the quarter ended Sept 30, 2026
- Lilly reports third-quarter 2026 financial results (BioSpace copy of the release)
Secondary sources
- Investing.com call transcript summary: consensus, prices, pricing, Medicare Bridge, Foundayo, capacity, 2027 and one-time items commentary
Marked, not independently confirmed
- The consensus figures of $5.60 EPS and $22.42B revenue, the price quotes, the $2B of non-recurring items, the U.S. price decline excluding rebate adjustments (10%), the Medicare Bridge figures, plant sizes and the 2027 commentary come from one call summary.
- That summary was unsure whether Foundayo is the product the call called orforglipron, and I used the name Foundayo only.
Where sources disagree
- The 10-Q cover shows 940.7M shares outstanding while weighted diluted shares are 893.4M and guidance assumes about 894M. I could not reconcile them.
- The release highlights say Merida Biosciences was completed after quarter end, while its news list says Lilly is to acquire it. The 10-Q calls it a subsequent event for up to $2.9B.
Left out
- Currency effects and Zepbound sales outside the U.S., which the extracts I read do not give.
- Any closing price after Oct 28, which I could not confirm.
- Litigation details, which are in notes I could not read.
Derived figures are my arithmetic from the filings and are marked (d), "derived" or "my arithmetic".

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Related Research
 DHR
Danaher (DHR): Core Sales Up 3% And Adjusted EPS Up 11.5%, But A Tax Swing Was 81% Of The Net Earnings Gain
 ISRG
Intuitive Surgical (ISRG): Non-GAAP EPS Up 25%, GAAP EPS Down 24%, And A $450M Settlement Explains Two-Thirds Of The Gap
 MRK
Discussion
Be the first to comment.