
Investment Thesis
Marvell agreed to acquire Lumentum in an all-stock transaction at 4.500 Marvell shares for each Lumentum share. The announcement implies $115B of enterprise value, about $1,132 per Lumentum share and a 23.9% premium to unaffected prices. Lumentum holders would own 33% of the combined company, while Marvell holders retain 67%. With closing expected only in the first half of 2028, value depends on the relative share prices, regulatory completion and realization of more than $1B in annual run-rate cost synergies.
- Consideration. 4.500 MRVL shares for each LITE share.
- Implied value. $115B enterprise value and about $1,132 per LITE share.
- Premium. 23.9% to October 28 unaffected closing prices.
- Ownership. MRVL 67%, LITE 33% on a fully diluted basis.
- Timing. Expected close in the first half of 2028.
- This article contains no rating, price target or investment advice. Derived figures are marked (d).
Bottom line. This is not a fixed-dollar offer. Lumentum holders receive a fixed number of Marvell shares, so the deal value moves with MRVL until closing. The long timetable makes integration promises less immediate and market/regulatory risk more important.
Source: Marvell-Lumentum transaction announcement (8-K Ex. 99.1).
2026 Transaction At A Glance
| Deal term | Value |
|---|---|
| Exchange ratio | 4.500 MRVL per LITE |
| Implied enterprise value | $115B |
| Implied value per LITE share | $1,132 |
| Premium | 23.9% |
| Pro forma ownership | 67% MRVL / 33% LITE |
| Expected close | First half 2028 |
Source: Marvell-Lumentum transaction announcement (8-K Ex. 99.1). Derived figures are marked (d).
What The Market Believes vs. What The Data Actually Shows
| Belief | What the data show |
|---|---|
| LITE holders locked in $1,132 per share | They are locked into 4.5 MRVL shares; dollar value floats with MRVL. |
| The 23.9% premium is protected | A fixed exchange ratio preserves relative ownership, not the original dollar premium. |
| The combination is immediately accretive | Management expects non-GAAP EPS accretion in year one after closing, which is not expected until 2028. |
| The synergy target is small relative to the deal | $1B is meaningful, but only 0.9% of the implied $115B enterprise value per year (d). |
Forensic #1: Fixed Ratio, Floating Value
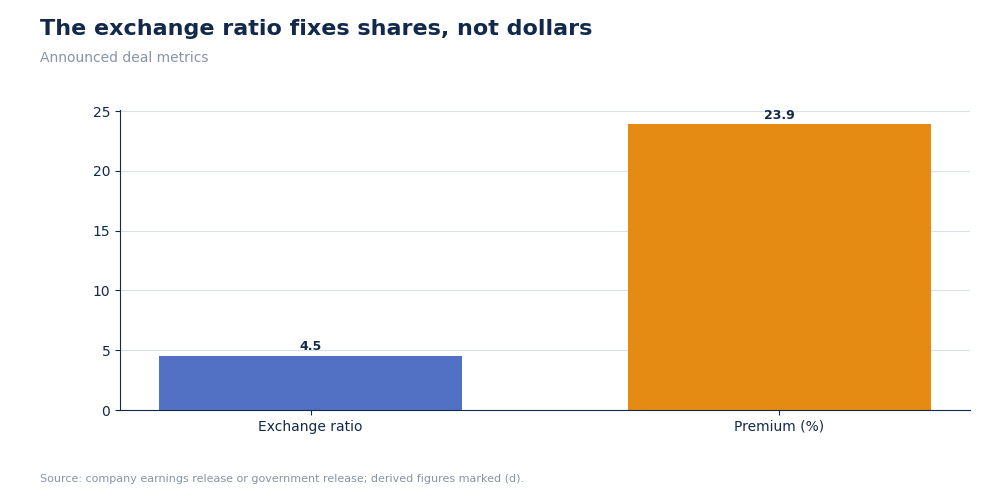
In an all-stock fixed-ratio merger, target holders receive a fixed number of buyer shares. Dollar consideration changes with the buyer share price.
| Term | Value |
|---|---|
| Exchange ratio | 4.500 MRVL shares |
| Implied value at announcement | $1,132/LITE share |
| Premium to unaffected prices | 23.9% |
| Cash component | $0 stated |
Marvell-Lumentum announced transaction terms
The implied MRVL reference price is about $251.56 per share (d), calculated as $1,132 divided by 4.5. A 10% move in MRVL would move implied LITE consideration by about 10% before any spread change (d).
Why it matters. The headline $1,132 is a snapshot, not a guaranteed cash payment.
Source: Marvell-Lumentum transaction announcement (8-K Ex. 99.1)
Forensic #2: Ownership And Dilution
Pro forma ownership shows who bears integration risk and receives future synergies.
| Holder group | Pro forma ownership |
|---|---|
| Current Marvell holders | 67% |
| Current Lumentum holders | 33% |
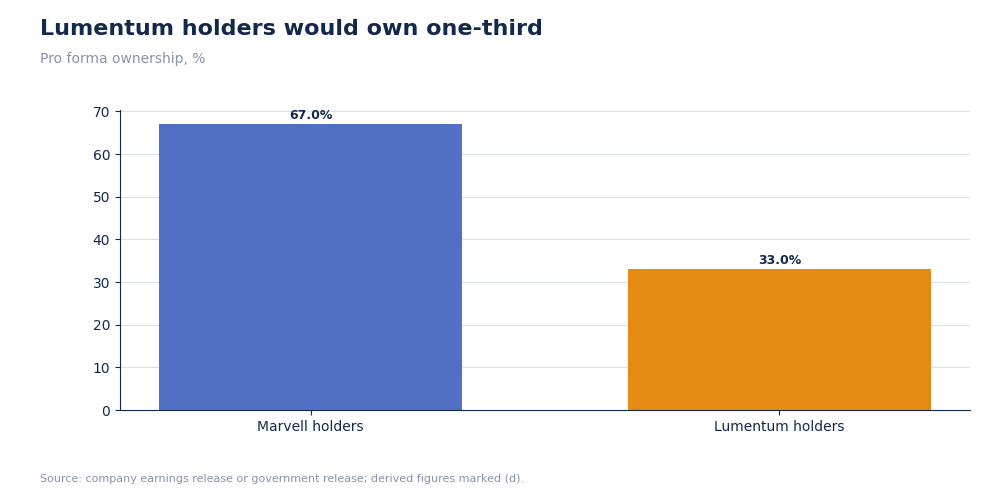
Pro forma ownership of combined Marvell-Lumentum
Lumentum holders receive one-third of the combined equity. That is economically consistent with a large acquisition but means Marvell holders give up 33% of the future company before synergies.
Why it matters. Synergy value must exceed dilution and integration cost for existing MRVL holders.
Source: Marvell-Lumentum transaction announcement (8-K Ex. 99.1)
Forensic #3: Synergy Scale
Run-rate cost synergy is an annual expense reduction after integration. Comparing it with enterprise value shows its scale, though not its present value.
| Measure | Value |
|---|---|
| Annual run-rate cost synergies | more than $1B |
| Implied enterprise value | $115B |
| Synergy / EV | more than 0.87% (d) |
| Addressable market | $550B |
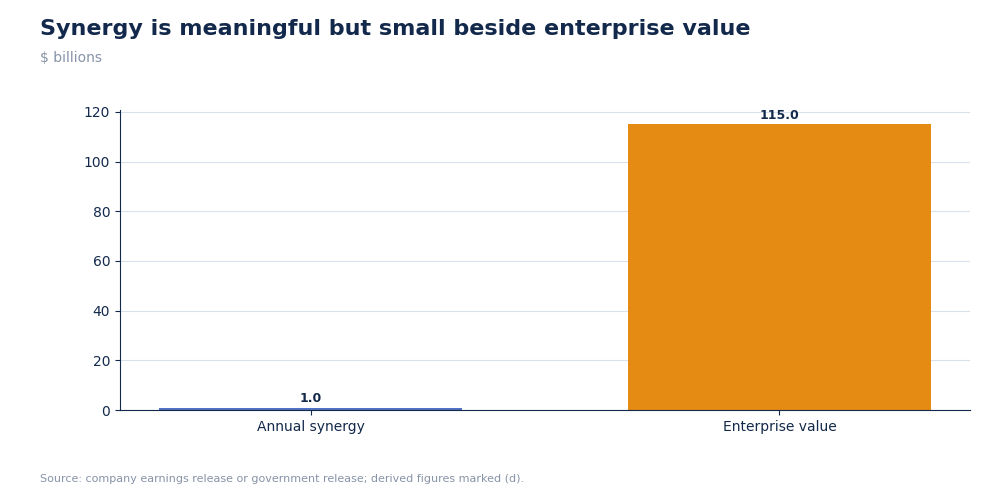
Announced synergy and transaction scale
A $1B annual saving is less than 1% of enterprise value but compounds if durable. The release gives no timing curve or one-time integration cost, so a present value cannot be verified.
Why it matters. The missing timing and cost-to-achieve matter as much as the run-rate headline.
Source: Marvell-Lumentum transaction announcement (8-K Ex. 99.1)
Forensic #4: Timetable And Information Risk
A long period between signing and closing increases exposure to regulatory change, customer reactions and market moves.
| Milestone | Status |
|---|---|
| Boards | Unanimously approved |
| Stockholder approvals | Required |
| Regulatory approvals | Required |
| Expected close | First half 2028 |
| Marvell fiscal Q3 2027 | Preliminary revenue only |
Marvell-Lumentum transaction timetable and conditions
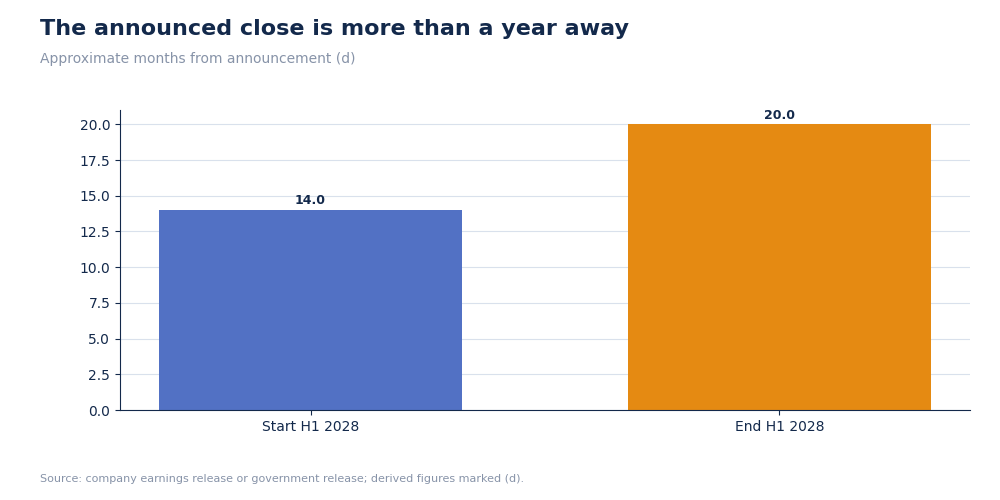
The expected close is roughly 14-20 months after announcement (d), depending on the exact date in the first half of 2028. During that interval, the fixed ratio exposes both groups to MRVL price movements.
Why it matters. A long close makes the deal spread compensation for time and completion risk, not just a premium calculation.
Source: Marvell-Lumentum transaction announcement (8-K Ex. 99.1)
Valuation Snapshot
At the latest quotes, MRVL traded at $171.41 and LITE at $684.40. The fixed 4.5 exchange ratio implies consideration of $771.35 per LITE share (d), creating a gross spread of 12.7% (d). The implied consideration is 31.9% below the $1,132 announcement value (d) because MRVL fell after the deal announcement.
| Measure | Value |
|---|---|
| MRVL share price | $171.41 |
| LITE share price | $684.40 |
| Exchange ratio | 4.500x |
| Current implied LITE consideration | $771.35 (d) |
| Gross deal spread | 12.7% (d) |
| Annualized spread over 14-20 months | 7.4%-10.8% (d) |
| Combined market capitalization | $223.74B (d) |
Investment read-through. This is now a merger-arbitrage problem, not a simple premium story. The 12.7% gross spread compensates investors for a long closing period, regulatory risk and MRVL price volatility. Because consideration floats with MRVL, a 10% MRVL decline would reduce implied LITE consideration to about $694.21 (d), nearly eliminating the current spread before any change in LITE.
What has to be true. The transaction must close within the first-half 2028 window, and the value of MRVL equity must remain high enough for the exchange ratio to compensate LITE holders.
Source: MRVL and LITE quotes and market capitalizations from the in-session U.S. equity market feed; transaction terms from the November 2, 2026 SEC exhibit. Market data: latest quote retrieved after the November 2, 2026 U.S. trading session.
Risks: What Would Break The Thesis
- Floating value. The offer falls in dollars if MRVL falls.
- Regulatory duration. Closing is not expected until 2028.
- Integration. Electrical and optical product roadmaps must be coordinated.
- Preliminary data. Marvell reported only preliminary fiscal Q3 revenue.
The deal case improves if customer overlap is limited and synergy capture begins quickly after closing.
What To Watch Next
- MRVL share price and implied LITE consideration.
- Regulatory and shareholder approvals.
- Progress toward the first-half 2028 close.
- Detailed synergy timing and one-time costs.
- Final Marvell fiscal Q3 2027 results.

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Related Research
 CMCSA
Comcast (CMCSA): Peacock's $478M Swing Drove Media Profit, While Broadband Lost 144K Customers And Free Cash Flow Fell 15%
 O
Realty Income’s 671 Consecutive Monthly Dividends And A 235bps Acquisition Spread Make The Rate-Sensitivity Label Wrong (O)
 PLTR
Discussion
Be the first to comment.