
Investment Thesis
Lockheed Martin reported third-quarter sales of $20,711M, up 11%, and diluted EPS of $7.97, up from $6.95. Backlog reached a record $291,984M, up 51% since year-end, almost entirely because Missiles and Fire Control backlog tripled to $142.5B on a PAC-3 MSE award. Behind the headline, no segment margin improved, F-35 deliveries fell, and free cash flow fell 10% to $2,999M. The company raised its full-year guidance, including free cash flow to $7.8B to $8.0B.
- Results. Sales $20,711M (+11%), consolidated operating profit $2,443M (+7%, margin 11.8% against 12.3%), net earnings $1,845M (+14%), diluted EPS $7.97 (+$1.02).
- Segments. Missiles and Fire Control sales $4,501M (+24%) at a 14.0% margin; Aeronautics $8,214M (+13%) at 9.0%; Rotary and Mission Systems $4,511M (+3%) at 11.6%; Space $3,485M (+4%) at 9.5%. Total segment profit $2,229M, margin 10.8% against 10.9%.
- Backlog. $291,984M against $193,622M at Dec 31, 2025. Missiles and Fire Control $142,517M against $46,650M. The release says $52.5B is tied to the PAC-3 MSE award and calls backlog up 27% since Q2.
- F-35. 43 deliveries in Q3 against 46, and 94 in nine months against 143. The company says costs on the Lot 20 advance contract began to exceed current authorization and funding.
- Cash. Cash from operations $3,438M against $3,728M, capex $439M, free cash flow $2,999M against $3,347M. Nine-month free cash flow $5,625M against $4,152M.
- Capital returns. Nine-month dividends $2,408M. No share repurchases in 2026 to date, against $2,250M in the first nine months of 2025.
- 2026 guide (raised). Sales about $80.0B to $82.0B, segment operating profit about $8,575M to $8,675M, EPS about $30.35 to $30.75, cash from operations $10.0B to $10.2B, free cash flow $7.8B to $8.0B.
- This article contains no price target or rating. Every figure comes from the named source, and anything I calculated is marked (d).
Bottom line. The record backlog is real and concentrated: Missiles and Fire Control accounts for about 97% of the increase since year-end (d). That makes Lockheed a different company from a year ago in terms of what is waiting to be built, with about 7.9 years of Missiles and Fire Control sales in backlog (d). The investor question is conversion, since the quarter's earnings improvement came with flat-to-lower margins, fewer F-35 deliveries and a lower free cash flow.
Source: Lockheed Martin Q3 2026 earnings release, SEC Exhibit 99.1.
Q3 2026 At A Glance
| Metric (Q3 2026) | Result | Change |
|---|---|---|
| Sales | $20,711M | +11% |
| Consolidated operating profit / margin | $2,443M / 11.8% | +7% / from 12.3% |
| Segment operating profit / margin | $2,229M / 10.8% | +10% (d) / from 10.9% |
| Net earnings | $1,845M | +14% |
| Diluted EPS | $7.97 | from $6.95 |
| Backlog | $291,984M | from $193,622M at Dec 31, 2025 |
| Cash from operations | $3,438M | -8% (d) |
| Free cash flow | $2,999M | -10% (d) |
| F-35 deliveries | 43 | from 46 |
Source: Lockheed Martin Q3 2026 earnings release. Changes marked (d) are my arithmetic on stated dollars.
What The Market Believes vs. What The Data Actually Shows
| Belief | What the release shows |
|---|---|
| Record backlog means broad demand | Missiles and Fire Control backlog rose $95.9B of the $98.4B total increase (d). Aeronautics backlog fell 3.5% (d). |
| Growth is lifting profitability | Revenue rose 11% and operating profit 7%. Segment margin was 10.8% against 10.9%, and no segment margin rose. |
| F-35 volume is growing | Deliveries were 43 against 46, and 94 against 143 for nine months, down 34% (d), although Aeronautics sales rose 13%. |
| Cash flow follows earnings | EPS rose 15% and free cash flow fell 10% (d) in the quarter. |
| Shareholder returns are growing | No buybacks so far in 2026 against $2,250M a year earlier, and dividends rose about 3% (d). |
The conventional narrative is that rising defence budgets are lifting every line. This release shows a strong missile business and a flat-to-weaker aircraft business, with an unresolved contract issue on the F-35 programme that the company itself flags as a risk.
Forensic #1: A Backlog Increase Of $98B, Almost All In One Segment
| Backlog, $M | Dec 31, 2025 | Sept 27, 2026 | Change (d) |
|---|---|---|---|
| Aeronautics | 59,435 | 57,331 | -2,104 |
| Missiles and Fire Control | 46,650 | 142,517 | +95,867 |
| Rotary and Mission Systems | 47,715 | 49,435 | +1,720 |
| Space | 39,822 | 42,701 | +2,879 |
| Total | 193,622 | 291,984 | +98,362 (+51%) |
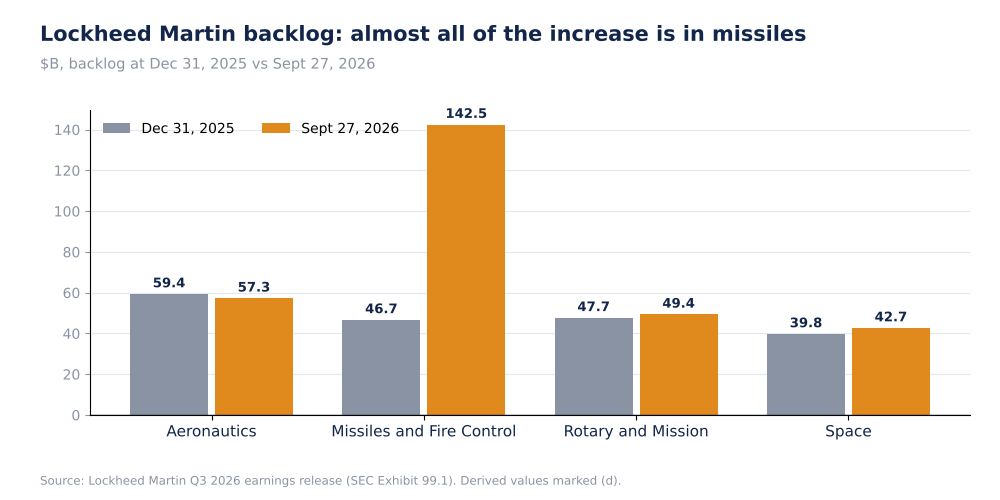
Lockheed Martin Backlog By Segment, $B (Self-Made)
The PAC-3 MSE award accounts for $52.5B of the missile backlog increase, which leaves about $43.4B (d) of the $95.9B from other awards that the extract does not itemise. At the Q3 sales run rate, Missiles and Fire Control backlog is about 7.9 years of segment sales (d, $4,501M times four), while Aeronautics backlog is about 1.7 years (d). The release calls backlog up 27% since Q2, which implies about $230B at the end of Q2 (d).
Why it matters. A multi-year award brings visibility, but backlog is not revenue or profit. A missile ramp needs production capacity and supplier capacity, and the margin on a new multi-year award is set by cost assumptions that have not yet been tested. The segment currently earns a 14.0% margin, the highest in the company, so the mix shift is helpful if that margin holds on the new work.
Source: Lockheed Martin Q3 2026 earnings release. Changes and years of sales are derived.
Forensic #2: Sales Grew 11% And No Segment Margin Improved
| Segment | Sales growth | Operating profit Q3 2026 | Margin Q3 2026 | Margin Q3 2025 |
|---|---|---|---|---|
| Aeronautics | +13% | $743M | 9.0% | 9.4% |
| Missiles and Fire Control | +24% | $631M | 14.0% | 14.1% |
| Rotary and Mission Systems | +3% | $524M | 11.6% | 11.6% |
| Space | +4% | $331M | 9.5% | 9.9% |
| Total segments | +11% | $2,229M | 10.8% | 10.9% |
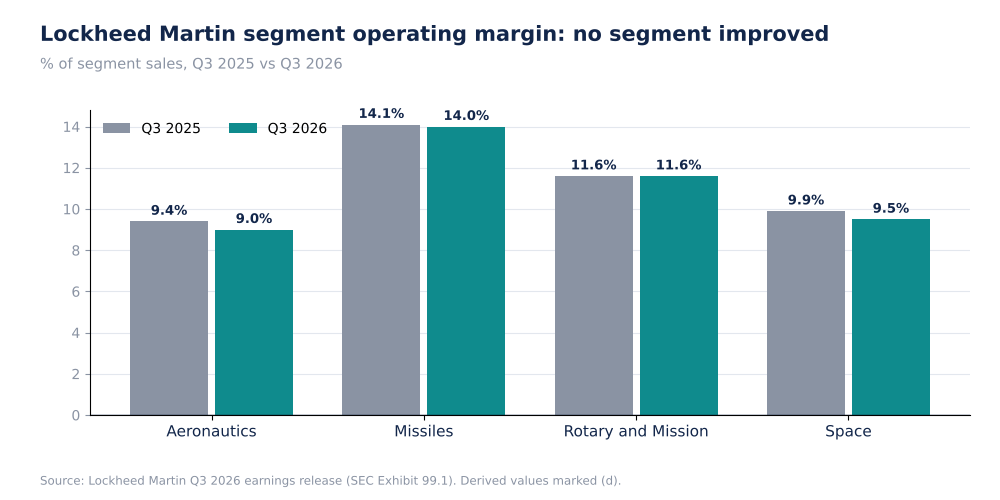
Lockheed Martin Segment Operating Margin, Q3 2025 vs Q3 2026 (Self-Made)
Space operating profit was $331M in both years on 4% higher sales. Segment profit grew about 10% (d) on 11% sales growth, so growth earned its average margin and no more. The release lists unfavourable profit adjustments of $40M on F-16, $40M on C-130 and $45M on Heavy Lift and Seahawk, partly offset by a favourable $40M adjustment in Rotary and Mission Systems, a net unfavourable $85M (d). Consolidated operating margin fell by 0.5 points, more than the segment margin, which means non-segment items were a drag of about $37M (d, $214M against $251M).
Why it matters. Fixed-price work is exposed to cost overruns, and these adjustments show that the programme risk is still present, even in a quarter with no reach-forward losses, against $1,615M in the first nine months of 2025. The comparison to last year is flattering for the same reason, so the earnings growth rate overstates operating improvement.
Source: Lockheed Martin Q3 2026 earnings release. Net adjustments and non-segment items are derived.
Forensic #3: F-35 Deliveries Fell, And Lot 20 Funding Is Unresolved
| Item | Q3 2026 | Prior year |
|---|---|---|
| F-35 deliveries, Q3 | 43 | 46 |
| F-35 deliveries, nine months | 94 | 143 |
| Nine-month delivery change (d) | -34% | n/a |
| Aeronautics sales increase from F-35 production and sustainment | +$710M | n/a |
| Aeronautics backlog | $57,331M | $59,435M at Dec 31, 2025 |
| Lot 20 and later contracts | still being negotiated | n/a |
Sales from F-35 production and sustainment rose even as deliveries fell, which can happen when revenue follows production activity and deliveries are a separate measure. The release says costs on the Lot 20 advance acquisition contract began to exceed current authorization and funding in Q3, and warns that without additional funding results and cash flows will be negatively affected. The size of the exposure is not given in the extract. A C-130 contribution of $270M of sales came from liquidating pre-contract costs tied to an anticipated Q3 award.
Why it matters. The F-35 is a major programme in Aeronautics, which is the largest segment at 40% of sales (d, $8,214M of $20,711M). A funding gap on an advance contract that is already spending is a cash risk, and negotiations on later lots determine pricing for years. It is the item in the release most plausibly linked to cash flow, though the release does not connect the two.
Source: Lockheed Martin Q3 2026 earnings release. The share of sales is derived.
Forensic #4: Cash Flow, Guidance And Capital Returns
| Item | Prior guide (July) | Current guide | Implied Q4 (d) |
|---|---|---|---|
| Sales | $79.75B to $81.75B | about $80.0B to $82.0B | n/a |
| Segment operating profit | $8,500M to $8,700M | about $8,575M to $8,675M | n/a |
| EPS | $29.95 to $30.65 | about $30.35 to $30.75 | n/a |
| Cash from operations | $9.2B to $9.4B | $10.0B to $10.2B | about $3.1B to $3.3B |
| Free cash flow | $7.0B to $7.2B | $7.8B to $8.0B | about $2.2B to $2.4B (Q3 was $3.0B) |
| Capex | $2.0B to $2.4B | $2.1B to $2.3B | n/a |
The free cash flow guide was raised by $0.8B at both ends, while the EPS midpoint rose $0.25, which is only about $58M of net earnings at 231M shares (d), so the guidance change looks mostly like cash timing, not earnings. The implied Q4 free cash flow of $2.2B to $2.4B is 21% to 27% below Q3 (d). Nine-month free cash flow is 36% higher than a year ago (d), helped by cash from operations of $6,893M against $5,338M. The company has not repurchased shares this year, and dividends of $2,408M for nine months use about 43% of nine-month free cash flow (d).
Why it matters. Cash flow for defence contractors can be lumpy, and a Q3 decline in a year with a large rise in guided cash implies a stronger Q4 collection. The absence of buybacks, against $2.25B last year, may indicate that management is preserving cash, which may relate to the F-35 funding question, though the release does not say so.
Source: Lockheed Martin Q3 2026 earnings release. Implied Q4 figures are full-year guidance less nine-month actuals where nine-month figures are stated (d).
Valuation Snapshot
TradingView shows Lockheed Martin at $622.99, up 5.13% on the day, with year-to-date gain of 31.44%. The page gives two market caps, $139.57B and $146.73B, so I also compute one from the release: $1,845M of net earnings at $7.97 a share implies about 231M diluted shares, and 231M times $622.99 is about $144B (d). The all-time high shown is $692.00 on Mar 2, 2026.
| Measure | Figure |
|---|---|
| Share price (TradingView) | $622.99 |
| Market cap (TradingView) | $139.57B or $146.73B (two figures on the page) |
| Market cap from price and implied shares (d) | about $144B |
| Price vs all-time high (d) | about -10% |
| Price / 2026 EPS guide midpoint ($30.55) (d) | about 20.4 times |
| 2026 free cash flow guide midpoint ($7.9B) / market cap (d) | about 5.5% (5.4% to 5.7% across the market caps) |
| Nine-month dividends annualised ($3.2B) / market cap (d) | about 2.2% |
A 5.5% free cash flow yield is attractive on its face, but the guide depends on a collection-heavy Q4 and on the F-35 funding outcome.
What has to be true. At about 20 times guided EPS and 10% below its March high, the price assumes the missile backlog converts at its current margin, F-35 funding is resolved without a charge, and aircraft deliveries recover. If any of those fails, a stock up 31% this year has little cushion beyond the cash yield.
Risks: What Would Break The Thesis
- F-35 Lot 20 funding. The company warns of negative effects on results and cash flow if additional funding is not provided.
- Backlog concentration. About 97% of the backlog increase is in one segment.
- Margins. Segment margin was flat to lower in every segment, with net unfavourable profit adjustments of about $85M.
- Q4 cash. The guide implies about $2.2B to $2.4B of Q4 free cash flow, and the raise is mostly timing.
- No buybacks. A shift from the $2.25B repurchased in the first nine months of 2025.
- Data limits. The extract did not include classified programme detail, segment guidance or the F-35 contract exposure.
The risk list is concrete: it is dominated by one programme and one segment, and each can be tracked through contract awards and quarterly disclosures.
What To Watch Next
- F-35 Lot 20 and later contract funding, and any charge or additional authorization.
- Missiles and Fire Control margin against 14.0%, and conversion of the $142.5B backlog.
- Aeronautics backlog and margin against $57.3B and 9.0%.
- Q4 free cash flow against the implied $2.2B to $2.4B.
- Reach-forward losses and profit adjustments on F-16, C-130, Heavy Lift and Seahawk.
- Whether share repurchases resume after none in the first nine months.

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Related Research
 HON
Honeywell (HON): Adjusted EPS Up 34%, GAAP EPS Down 20%, And Operating Cash Flow Down 74%
 GE
GE Aerospace (GE): Orders Up 49% And Adjusted EPS Up 36%, But Free Cash Flow Fell 14% And The Guide Implies A Softer Q4
 UPS
UPS: Revenue Up 6.7%, But The Adjusted Margin Fell A Full Point And U.S. Volume Dropped 3.3%
Latest earnings releases: LMT
— Lockheed Martin Reports Third Quarter 2026 Financial Results
Discussion
Be the first to comment.