
Investment Thesis
Coca-Cola grew third-quarter organic revenue 7% on 5% unit case growth, with comparable EPS of $0.91, up 11%. The growth was volume-led: price/mix added only 1% because four points of pricing were offset by three points of adverse mix, two points of the EPS growth was currency, and the CFO flagged a four-point revenue headwind in Q4 and an eight-point revenue headwind early in 2027 from refranchising.
- Growth. Organic revenue rose 7%, unit cases 5%, and price/mix 1%. Concentrate sales were described as two points ahead of unit case volume.
- Margins. Comparable gross margin rose about 170 basis points and comparable operating margin about 110 basis points.
- EPS. Comparable EPS was $0.91, up 11%, including a two-point currency benefit, so about 9% excluding currency (d).
- Cash and leverage. Year-to-date free cash flow was $11.4B. Net debt leverage was 1.3 times EBITDA, below a target range of two to 2.5 times.
- 2026 guide. Organic revenue growth of at least 5%, currency-neutral comparable EPS growth of at least 9%, and all-in comparable EPS growth of at least 11% against $3.00 in 2025, which is about $3.33 or more (d). Free cash flow is guided to at least $13B.
- Q4 and 2027. Six fewer days in Q4 and the CCBA refranchising create a four-point headwind to Q4 comparable net revenue and a three-point headwind to EPS. Early 2027 faces an eight-point revenue headwind and two-point EPS headwind from refranchising, plus a slight currency headwind at current rates.
- This article contains no price target or rating. Every figure comes from the executives' spoken remarks on the Q3 call or a named source, and anything I calculated is marked (d).
Bottom line. Coca-Cola is a steady compounder, with 5% volume growth, expanding margins and a balance sheet at 1.3 times EBITDA. The Q3 detail tells investors not to extrapolate: pricing was largely offset by mix, currency supplied part of the earnings growth, and 2027 faces a structural revenue headwind from refranchising. At about 28 times guided EPS, the stock leaves little room for a miss on those.
Source: Coca-Cola Q3 2026 earnings call transcript, Motley Fool, Oct 27, 2026.
Q3 2026 At A Glance
| Metric (Q3 2026) | Result |
|---|---|
| Organic revenue growth | +7% |
| Unit case volume | +5% |
| Price/mix | +1% (pricing +4 pts, mix -3 pts) |
| Concentrate sales | two points ahead of unit case volume |
| Comparable gross margin | up about 170 bp |
| Comparable operating margin | up about 110 bp |
| Comparable EPS | $0.91, +11% (includes +2 pts currency) |
| Free cash flow, year to date | $11.4B |
| Net debt leverage | 1.3x EBITDA (target 2 to 2.5x) |
| North America volume | even (flat) |
| Africa (EMEA) | high single-digit volume growth |
| India | each top-10 brand growing double digits; Sprite volume nearly +20% |
Net revenue dollars, operating cash flow and capex were not spoken, so I show none. Source: Coca-Cola Q3 2026 call transcript.
What The Market Believes vs. What The Data Actually Shows
| Belief | What the call shows |
|---|---|
| Coke has pricing power | Pricing added four points but mix took three away, leaving price/mix at +1%. |
| EPS growth is operating | Comparable EPS grew 11%, of which two points were currency (d: about 9% underlying). |
| Growth is global | North America volume was flat; growth came from Africa, India and other markets named on the call. |
| Next year is easy | Early 2027 has an eight-point revenue headwind and a two-point EPS headwind from CCBA refranchising. |
| The balance sheet is stretched | Net debt is 1.3 times EBITDA, below the two to 2.5 times target; capital return is primarily through dividends. |
The call gave no consensus; prices are in the Valuation Snapshot.
Coca-Cola's reputation is for pricing power. Q3 shows growth coming mostly from volume, with 110 basis points of operating margin gain on top, but price/mix added only 1%.
Forensic #1: Growth Came From Volume, Not Price/Mix
| Component | Q3 2026 |
|---|---|
| Organic revenue | +7% |
| Unit cases | +5% |
| Price/mix | +1% |
| Comparable EPS | +11% |
| Comparable EPS, excluding about 2 pts currency (d) | about +9% |
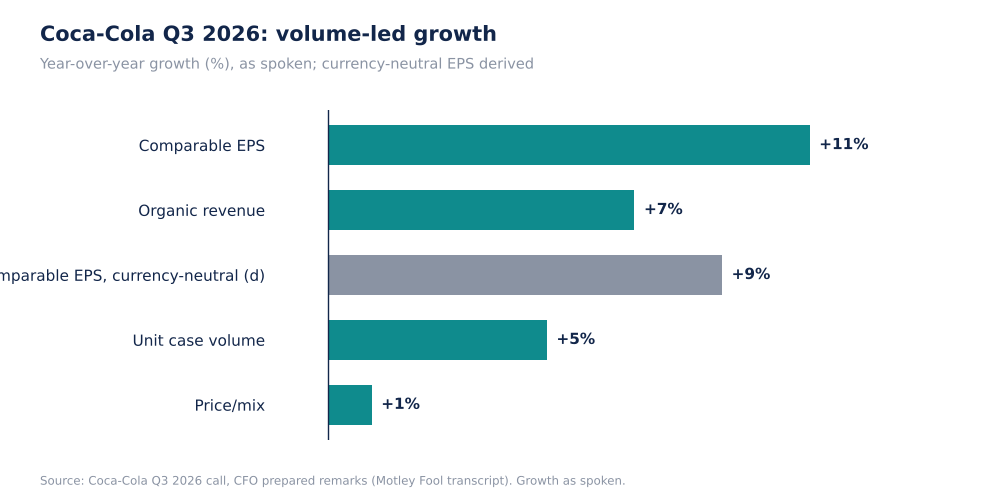
Coca-Cola Q3 2026 Growth In Organic Revenue, Volume, Price/Mix And EPS (Self-Made)
Organic revenue of 7% is more than unit cases (5%) plus price/mix (1%), which together are 6%; the spoken remarks do not reconcile the one-point difference, and concentrate sales were described as two points ahead of unit cases. The gap can reflect timing between concentrate shipments and bottler sales, but the call does not say so.
Why it matters. Volume-led growth is lower quality than price-led growth if it needs promotion or lower-margin packages, but a margin gain of 110 basis points shows Q3 volume did not dilute profitability. The one-point gap between organic revenue and unit cases plus price/mix is a reconciliation item worth asking the company about.
Source: Coca-Cola Q3 2026 call transcript.
Forensic #2: Pricing Of Four Points Was Offset By Three Points Of Mix
| Price/mix element | Points |
|---|---|
| Pricing | +4 |
| Mix | -3 |
| Price/mix | +1 |
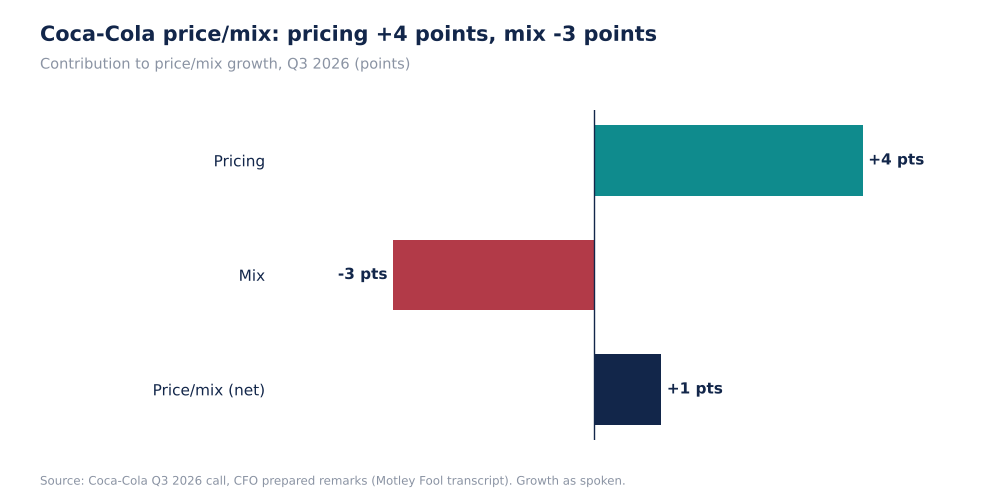
Coca-Cola Q3 2026 Price/Mix Components, Points (Self-Made)
Growth in volume of 5% with price/mix of 1% means revenue growth depends on units. The CFO also cited a two-year year-to-date volume growth average of 2%; the call does not say how that compares with the 5% in Q3.
Why it matters. A 3-point mix drag against 4 points of pricing suggests consumers are choosing smaller or lower-priced packages, or growth is skewed to lower-priced markets such as India and Africa, where management reported strong growth. The call did not say which, so treat this as a hypothesis to test.
Source: Coca-Cola Q3 2026 call transcript.
Forensic #3: The 2026 EPS Guide In Dollars
| Item | Percent | Dollars on $3.00 (d) |
|---|---|---|
| 2025 comparable EPS | n/a | $3.00 |
| Currency-neutral growth, excluding acquisitions and divestitures | at least 9% | +$0.27 |
| Currency tailwind | about 3 pts | +$0.09 |
| Divestiture headwind | about 1 pt | -$0.03 |
| All-in comparable EPS growth | at least 11% | at least about $3.33 |
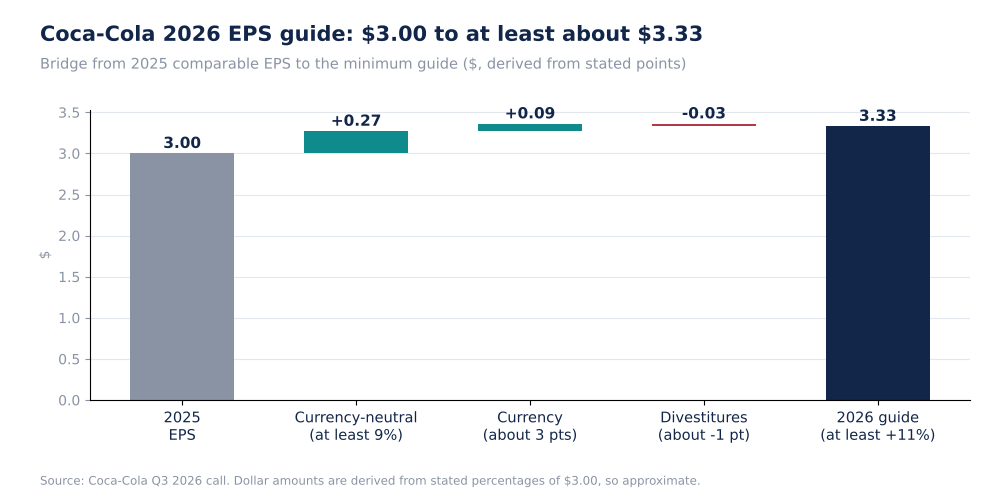
Coca-Cola 2026 Comparable EPS Guide Bridge, $ (Self-Made)
The percentages add as 9 + 3 - 1 = 11, matching the stated all-in guide. Currency is therefore about a quarter of the guided EPS growth (d). Revenue also faces a divestiture headwind of about 2% and a currency tailwind of about 1 point.
Why it matters. Of the 11% minimum guided EPS growth, about 9 points is underlying and about 3 points is currency, with divestitures taking about 1 point away. If the currency effect reverses, EPS growth falls toward 9%. The guide is a floor, since management said at least, not a forecast.
Source: Coca-Cola Q3 2026 call transcript. Dollar amounts are derived from stated percentages of $3.00 and are approximate.
Forensic #4: Refranchising Headwinds And Cash
| Item | Figure |
|---|---|
| Q4: six fewer days, CCBA effect | -4 pts to revenue, -3 pts to EPS |
| Early 2027: CCBA refranchising | -8 pts to revenue, -2 pts to EPS |
| 2026 free cash flow guide | at least $13B |
| Year-to-date free cash flow | $11.4B |
| Implied Q4 free cash flow at the guide (d) | at least about $1.6B |
| Share of the $13B delivered year to date (d) | about 88% |
| Underlying effective tax rate | 19.7% |
The guide for 2027 was limited to these headwinds; formal 2027 guidance was not given. The refranchising effect on revenue (8 points) is four times its effect on EPS (2 points), which is consistent with that revenue carrying less profit per dollar than the company average (d); I did not verify this.
Why it matters. Refranchising cuts reported revenue sharply (8 points in early 2027) but EPS by only 2 points, so it improves the margin of the remaining business even as headline growth looks weak. Investors comparing reported revenue growth in 2027 should adjust for it.
Source: Coca-Cola Q3 2026 call transcript.
Valuation Snapshot
TradingView shows Coca-Cola at $92.82, up 1.2% on the day and 32.9% year to date, about 2.7% below its all-time high of $95.37 on Oct 22. Market cap is about $394.7B and indicated dividend yield about 2.3%.
| Measure | Figure |
|---|---|
| Share price (TradingView) | $92.82 |
| Market cap (TradingView) | about $394.7B |
| P/E, trailing (TradingView) | 27.1 |
| Price / 2026 comparable EPS guide minimum of about $3.33 (d) | about 27.9x |
| 2026 free cash flow guide of at least $13B / market cap (d) | about 3.3% |
| Dividend yield (TradingView) | about 2.3% |
| Net debt leverage (call) | 1.3x EBITDA |
The shares are priced at about 28 times the minimum EPS guide, with 2026 growth in EPS guided to at least 11%, of which about 3 points is currency, and 2027 facing an eight-point revenue headwind. A free cash flow yield of about 3.3% is the cushion.
What has to be true. At about 28 times guided EPS and near an all-time high, the shares price in the guide being met or exceeded and the 2027 headwinds being absorbed. The 3.3% free cash flow yield and 2.3% dividend yield give some floor, and leverage of 1.3 times against a target range of 2 to 2.5 times gives capacity for returns.
Risks: What Would Break The Thesis
- Mix keeps offsetting pricing. Three points of adverse mix took away three-quarters of the pricing.
- Refranchising. An eight-point revenue headwind in early 2027.
- Currency. About 3 points of the 11% guided EPS growth is currency, and 2027 has a slight headwind at current rates.
- North America volume. Flat in Q3.
- Data limits. The release was not read; net revenue dollars were not spoken.
The risks concern growth quality: volume depends on strong emerging-market growth while North America was flat, and currency can add or subtract several points of EPS.
What To Watch Next
- Price/mix against +1% and the pricing-versus-mix split.
- Q4 comparable revenue and EPS with the six-fewer-days effect.
- Concentrate sales against unit case volume.
- 2027 guidance after the refranchising effect.
- Free cash flow against the guide of at least $13B.

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Related Research
 PG
Procter & Gamble (PG): Organic Sales Up 4% On Volume, But Core Gross Margin Fell 150 Bp And Costs Cap FY27 EPS Growth
 GIS
General Mills Beat Estimates By 16% But The Market Saw Only The Impairment — The $3B Cost Program Is Being Ignored (GIS)
 KHC
Kraft Heinz's 7% Yield Is Priced For A Dividend Cut The Cash Flow Doesn't Support (KHC)
Latest earnings releases: KO
— Coca-Cola Reports Third Quarter 2026 Results and Raises Full Year Guidance
Discussion
Be the first to comment.