
Investment Thesis
Boeing's third quarter was its best delivery quarter since 2018, with 161 commercial airplanes, revenue up 4% to $24.2B and positive free cash flow of $464M. But the 1.5% operating margin included a $252M gain on the sale of HRL Laboratories, Commercial Airplanes still lost money at a -6.5% margin, and management's free cash flow targets of $2B in 2026 rising to $10B in 2029 depend on the 777X being certified by mid-2027.
- Results. Revenue was $24.2B (+4%), operating margin 1.5% and core loss per share $0.34, all improved year over year. Free cash flow was $464M after roughly $700M of Department of Justice settlement payments.
- Gain inside the margin. The defense segment margin of 6.2% included a $252M gain on the HRL sale. Without it, defense margin was about 3.0% and company operating margin about 0.5% (d, approximate).
- Commercial. Commercial Airplanes revenue was $10.7B (-3%) at a -6.5% margin, about -$0.7B of operating loss (d). Deliveries were 161, of which 124 were 737s and 22 were 787s.
- Backlog. Total backlog was a record $745B: $612B commercial (over 6.3 thousand airplanes), $101B defense and $33B services.
- Rates. The 737 is stabilising at 47 a month, which the CEO said is taking longer than expected, with rate 52 targeted for the back half of 2027. The 787 is at 8 a month and moving to 10. The 777X is about 1 a month with first delivery in 2027.
- Balance sheet. Cash and marketable securities were $20.7B and debt $45.9B, so net debt was about $25.2B (d). There is a $10B undrawn revolver.
- Cash targets. Free cash flow is guided to about $2B in 2026, about $3B in 2027, about $6B in 2028 and $10B in 2029, assuming 777X certification by mid-2027.
- This article contains no price target or rating. Every figure comes from the executives' spoken remarks on the Q3 call or a named source, and anything I calculated is marked (d).
Bottom line. Boeing's Q3 is operationally better, with the most deliveries since 2018 and positive free cash flow, but financially it is still a turnaround. The profit is in defense and services, commercial remains loss-making, and the $10B cash target for 2029 depends on rate increases and a certification that management itself says are taking longer than expected.
Source: Boeing Q3 2026 earnings call transcript, Motley Fool, Oct 27, 2026.
Q3 2026 At A Glance
| Metric (Q3 2026) | Result | Change |
|---|---|---|
| Revenue | $24.2B | +4% |
| Operating margin | 1.5% | improved year over year |
| Core EPS | -$0.34 | improved year over year |
| Free cash flow | $464M | improved; after about $700M DOJ payments |
| Cash and marketable securities | $20.7B | n/a |
| Debt | $45.9B | unchanged from Q2 |
| Commercial Airplanes revenue / margin | $10.7B / -6.5% | revenue -3%; margin improved |
| Defense, Space & Security revenue / margin | $7.9B / 6.2% | revenue +15%; includes $252M gain |
| Global Services revenue / margin | $5.6B / 18.3% | revenue +4% (+11% excl. divestiture) |
| Commercial deliveries | 161 | most since 2018 |
| 737 / 787 deliveries | 124 / 22 | n/a |
| Backlog (total) | $745B | record |
Prior-year EPS and free cash flow were not spoken in the prepared remarks, so I show none. Source: Boeing Q3 2026 call transcript.
What The Market Believes vs. What The Data Actually Shows
| Belief | What the call shows |
|---|---|
| Boeing is back to profit | Operating margin was 1.5% including a $252M gain; core EPS was still a $0.34 loss. |
| Commercial is recovering | Deliveries were the most since 2018, but the segment margin was -6.5% and revenue fell 3%. |
| Cash flow has turned | Free cash flow was $464M after $700M of DOJ payments, but the 2026 target is only about $2B. |
| Rate 52 is near | The 737 is at 47 a month, taking longer than expected, with rate 52 targeted for the back half of 2027. |
| The balance sheet is healthy | Debt is $45.9B against $20.7B of cash, so net debt is about $25.2B (d). |
The call gave no consensus; prices are in the Valuation Snapshot.
The recovery narrative rests on deliveries. The call supports that on volume, but the financials show a mix in which Boeing's largest division loses 6.5% of revenue while the smaller divisions earn the profit.
Forensic #1: A $252M Gain Sits Inside The Margin
| Item | Reported | Excluding $252M gain (d, approximate) |
|---|---|---|
| Defense, Space & Security margin | 6.2% (about $490M) | about 3.0% (about $238M) |
| Company operating margin | 1.5% (about $363M) | about 0.5% (about $111M) |
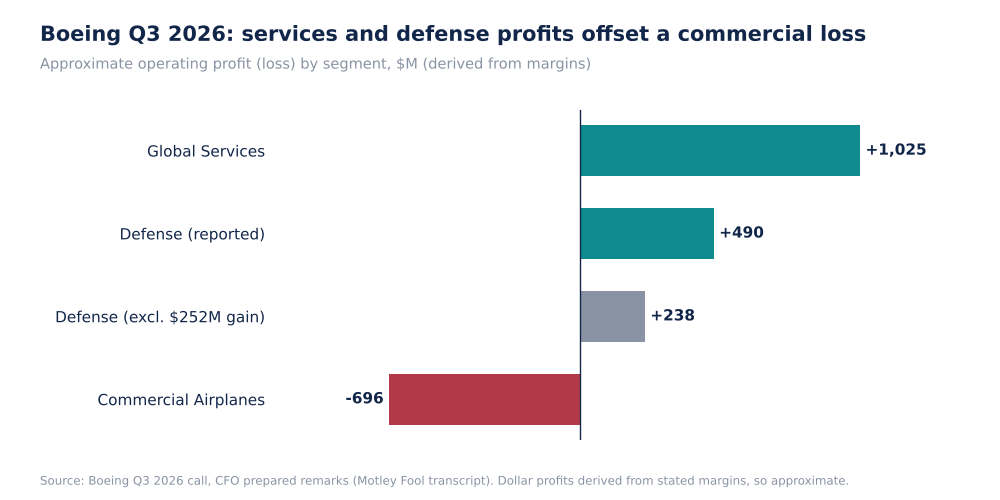
Boeing Q3 2026 Approximate Segment Operating Profit (Loss), $M, Derived From Margins (Self-Made)
Dollar profits are my arithmetic from rounded margins, so they are approximate. Segment profits add to about $0.8B (d) against about $0.4B at the company level, so unallocated and other items are about -$0.45B (d). Global Services margin was 18.3% on $5.6B of revenue.
Why it matters. Removing the $252M gain turns a 1.5% company margin into about 0.5% (d), and the defense margin from 6.2% to about 3.0%. Global Services, at 18.3%, is the highest-quality profit stream and the smallest of the three. Investors valuing Boeing on a margin target should anchor on the underlying figure.
Source: Boeing Q3 2026 call transcript.
Forensic #2: Deliveries Rose, But The Commercial Segment Still Lost Money
| Item | Q3 2026 |
|---|---|
| Total commercial deliveries | 161 |
| 737 | 124 |
| 787 | 22 |
| 767, 777 and other (d) | 15 |
| Commercial Airplanes revenue | $10.7B (-3%) |
| Commercial Airplanes margin | -6.5% |
| Backlog | $612B, over 6.3 thousand airplanes |
| Backlog in years at 161 a quarter (d) | about 9.8 |
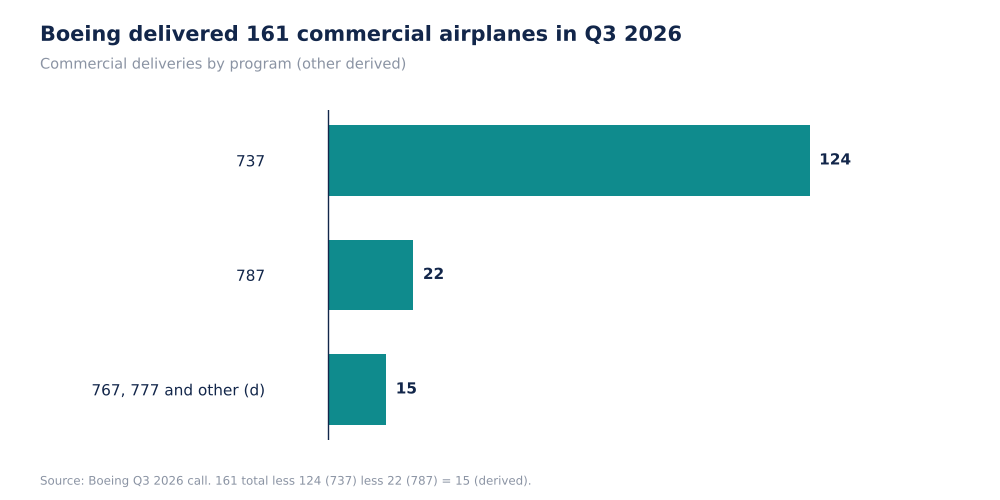
Boeing Q3 2026 Commercial Deliveries By Program (Self-Made)
The CFO attributed the revenue decline to a less favourable delivery mix. A wing component supplier disrupted 777 freighter and 767 tanker lines, with a cost the CFO called "not material in the third quarter" but to be treated as abnormal production expense over the next few quarters. The 2026 expectation is 90 to 100 787 deliveries, near the lower end, and 737 deliveries short of 500.
Why it matters. On 161 deliveries, Commercial Airplanes earned about $66M of revenue per delivery and lost about $4.3M per delivery (d, rough, because the segment includes revenue not tied to deliveries). The route to profit is production rate, which spreads fixed costs over more airplanes, and that is why the 737 and 787 rate milestones matter more than the order book.
Source: Boeing Q3 2026 call transcript.
Forensic #3: The Free Cash Flow Path Depends On The 777X
| Year | Free cash flow (management) |
|---|---|
| Q3 2026 (actual) | $464M, after about $700M DOJ payments |
| 2026 | about $2B |
| 2027 | about $3B |
| 2028 | about $6B |
| 2029 | $10B |
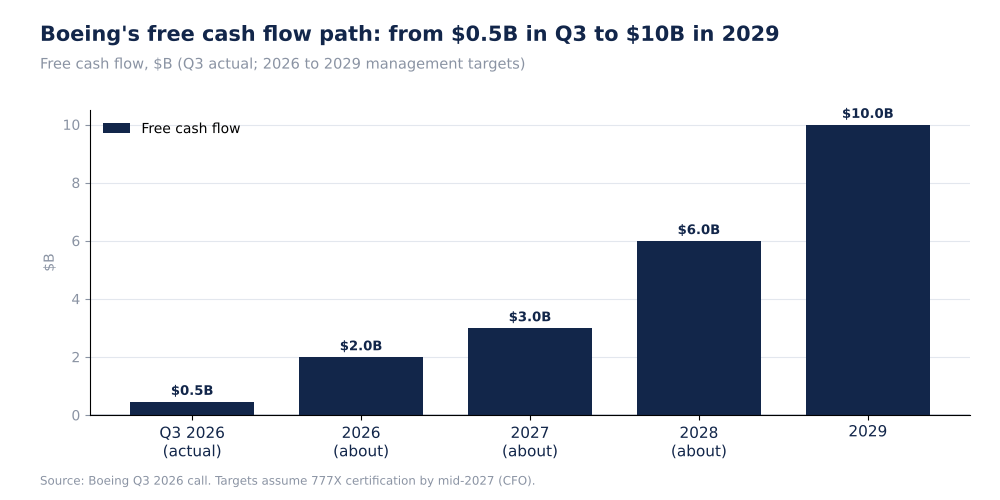
Boeing Free Cash Flow: Q3 2026 Actual And Management Targets, $B (Self-Made)
The CFO named the 2027 drivers: no repeat of the DOJ payment, higher commercial deliveries and better cash margins, partly offset by less favourable working capital and about $1B of higher capex. The targets assume 777X certification by mid-2027, and the 777X first delivery is in 2027. Excluding the DOJ payments, Q3 free cash flow would have been about $1.16B (d).
Why it matters. The targets are back-loaded: the four figures sum to $21B, of which $16B, about 76%, falls in 2028 and 2029 (d). That makes the valuation depend on delivery and certification milestones in 2027, and it explains why investors are paying about 13 times the 2029 target but about 66 times the 2026 target.
Source: Boeing Q3 2026 call transcript.
Forensic #4: Backlog And Balance Sheet
| Item | Amount |
|---|---|
| Commercial backlog | $612B (82% of total, d) |
| Defense backlog (FA-XX excluded) | $101B |
| Services backlog | $33B |
| Total, as stated | $745B |
| Sum of the three (d) | $746B |
| Cash and marketable securities | $20.7B |
| Debt | $45.9B |
| Net debt (d) | $25.2B |
| Undrawn revolver | $10B |
| Defense orders in Q3 | $23B |
Commercial Airplanes is 44% of revenue but 82% of backlog (d), so the delivery rate path drives most of the long-term value. Backlog of $745B is about 31 times quarterly revenue (d).
Why it matters. Net debt of $25.2B is 12.6 times the 2026 free cash flow target of $2B (d), so deleveraging is a multi-year process even if the targets are met. The $745B backlog is a strength, but converting it requires production rate gains, not new orders.
Source: Boeing Q3 2026 call transcript.
Valuation Snapshot
TradingView shows Boeing at $167.14, down 10.7% on the day (undated), with a market cap of about $132.9B and year-to-date change of -22.9%. The page's P/E of 85.8 does not reconcile with its own price and EPS, so I do not use it.
| Measure | Figure |
|---|---|
| Share price (TradingView) | $167.14 |
| Market cap (TradingView) | about $132.9B |
| Net debt (d, $45.9B debt less $20.7B cash) | $25.2B |
| Enterprise value, approximate (d) | about $158B |
| Enterprise value / annualised Q3 revenue of $96.8B (d) | about 1.6x |
| Market cap / 2026 free cash flow target of about $2B (d) | about 66x |
| Market cap / 2029 free cash flow target of $10B (d) | about 13.3x, undiscounted |
| Year to date (TradingView) | -22.9% |
Investors are paying about 13 times a 2029 cash flow target that depends on 777X certification by mid-2027, and about 66 times the 2026 target. Core EPS is negative, so earnings multiples are not meaningful.
What has to be true. The price implies that investors believe much of the 2029 cash flow target. TradingView shows a one-day fall of about 11% on the page (undated), which illustrates how sensitive the shares are to delivery and cash flow news. The next milestones are the 737 rate and 777X certification.
Risks: What Would Break The Thesis
- 777X certification slips. The cash targets assume mid-2027.
- 737 rate 52. It is taking longer than expected to show rate 47 performance.
- Supplier disruption. A wing component issue touches 777 freighter and 767 tanker lines.
- Defense gains do not repeat. The $252M gain lifted Q3 defense margin.
- Data limits. The release was not read; prior-year EPS and free cash flow were not spoken.
Most risks are about timing. Slips in 777X certification, 737 rate 52 or supplier issues each defer cash flow rather than destroy it, but with $45.9B of debt, deferral has a financing cost.
What To Watch Next
- Commercial Airplanes margin against -6.5%.
- 737 rate against 47 a month, and the path to 52.
- 777X certification progress against mid-2027.
- Q4 free cash flow against the 2026 target of about $2B.
- Defense margin without the HRL gain.

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Related Research
 BA
Boeing Out-Delivered Airbus For The First Time Since 2019 — The Production Ramp Math Says $275 (BA)
 HON
Honeywell (HON): Adjusted EPS Up 34%, GAAP EPS Down 20%, And Operating Cash Flow Down 74%
 GE
Discussion
Be the first to comment.