
Investment Thesis
Backblaze grew Q3 2026 revenue 26% to $46.7M because B2 Cloud Storage rose 47% to $30.5M, while Computer Backup fell 2% to $16.2M. Gross margin rose to 64% and adjusted EBITDA margin to 33%, yet nine-month adjusted free cash flow was only $1.9M. The company issued $201.25M of 0% convertible notes, materially changing the balance sheet to fund contracted growth and capital expenditure.
- Revenue. $46.7M, +26%.
- Mix. B2 $30.5M, +47%; Backup $16.2M, -2%.
- Margins. GAAP gross margin 64%; adjusted EBITDA margin 33%.
- Retention. B2 NRR 115%; Backup NRR 94%.
- Financing. $201.25M convertible notes; $194.5M long-term debt at quarter-end.
- This article contains no rating, price target or investment advice. Derived figures are marked (d).
Bottom line. The business is becoming a B2 storage company faster than the consolidated growth rate suggests. The trade-off is capital intensity: adjusted EBITDA is strong, but free cash flow is thin and external financing supplied most of the new cash.
Source: Backblaze Q3 2026 earnings release (8-K Ex. 99.1).
Q3 2026 At A Glance
| Measure | Q3 2026 | Q3 2025 |
|---|---|---|
| Revenue | $46.7M | +26% |
| B2 revenue | $30.5M | +47% |
| Backup revenue | $16.2M | -2% |
| Gross margin | 64% | 62% |
| Net loss | -$2.4M | -$3.8M |
| Adjusted EBITDA | $15.2M | $8.4M |
Source: Backblaze Q3 2026 earnings release (8-K Ex. 99.1). Derived figures are marked (d).
What The Market Believes vs. What The Data Actually Shows
| Belief | What the data show |
|---|---|
| All products are growing | Backup revenue and ARR both fell 2%. |
| Adjusted EBITDA means the business self-funds | Nine-month adjusted free cash flow was only $1.9M. |
| Customer retention is uniformly strong | B2 NRR was 115%, but Backup NRR was 94%. |
| The larger cash balance came from operations | The $201M convertible note issue drove most of the increase. |
Forensic #1: Growth By Product
A blended growth rate can hide a fast-growing product and a shrinking legacy product. Mix determines the future margin and retention profile.
| Product | Q3 revenue | Growth | Share (d) |
|---|---|---|---|
| B2 Cloud Storage | $30.5M | +47% | 65% |
| Computer Backup | $16.2M | -2% | 35% |
| Total | $46.7M | +26% | 100% |
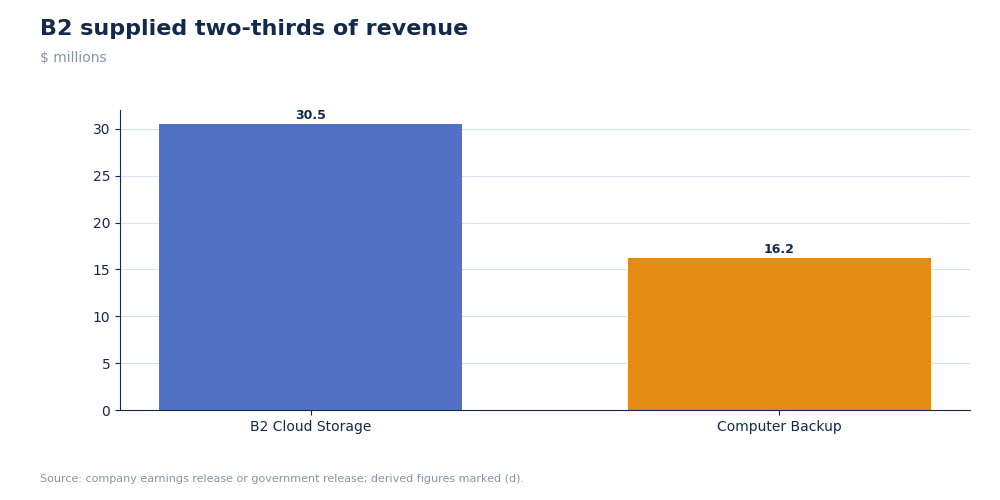
Backblaze revenue by product, Q3 2026
B2 supplied 65% of revenue (d) and all consolidated growth; without it, the company would have contracted. The shift is accelerating because B2 ARR grew 53%.
Why it matters. The consolidated business is being redefined by B2, while the legacy line is a drag.
Source: Backblaze Q3 2026 earnings release (8-K Ex. 99.1)
Forensic #2: ARR And Retention Quality
ARR measures the annualized run rate, while net revenue retention shows expansion or contraction inside the customer base.
| Metric | B2 | Backup | Total |
|---|---|---|---|
| ARR | $126.8M | $63.9M | $190.7M |
| ARR growth | +53% | -2% | +29% |
| NRR | 115% | 94% | 105% |
| Gross retention | 89% | 91% | 91% |
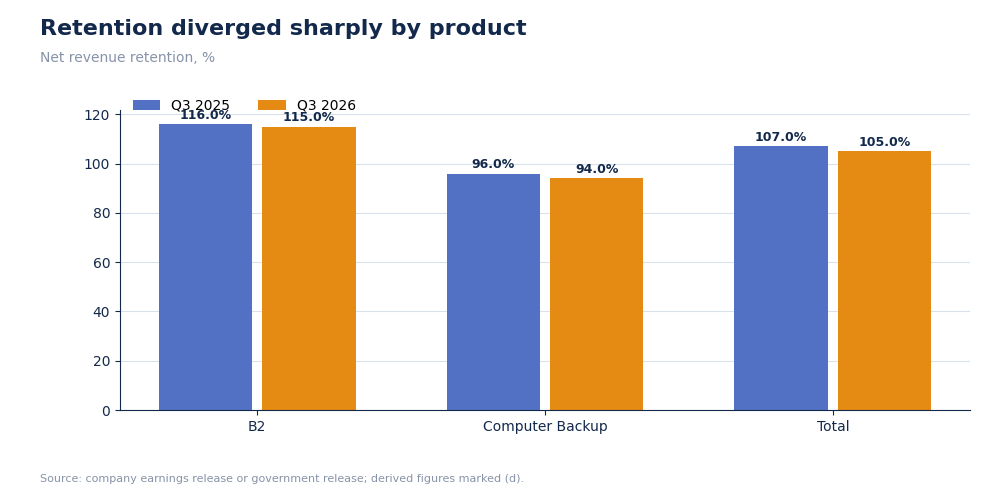
Backblaze net revenue retention by product
B2 customers expanded spending by 15% net of churn, while Backup customers contracted 6%. Total NRR fell from 107% to 105%, despite faster B2 growth, because mix transition and legacy contraction still matter.
Why it matters. Retention shows whether growth comes from durable expansion or repeated new-customer acquisition.
Source: Backblaze Q3 2026 earnings release (8-K Ex. 99.1)
Forensic #3: Adjusted Profit Versus Cash
Adjusted EBITDA removes depreciation, stock compensation and other items. For storage infrastructure, depreciation and capex are economically important, so cash conversion is the harder test.
| Measure | Q3 / YTD 2026 |
|---|---|
| Q3 adjusted EBITDA | $15.2M |
| Q3 adjusted EBITDA margin | 33% |
| Nine-month operating cash flow | $22.8M |
| Nine-month capex + capitalized software | $12.3M (d) |
| Nine-month adjusted free cash flow | $1.9M |
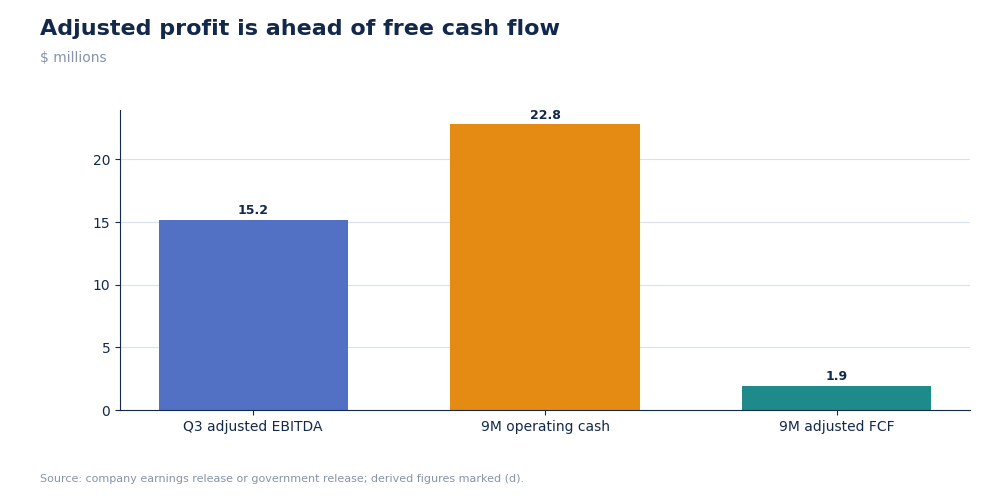
Backblaze adjusted EBITDA and nine-month cash measures
Nine-month operating cash flow improved, but adjusted free cash flow was only $1.9M after capex definitions and other adjustments. Property and equipment plus capitalized software spending totaled $12.3M (d).
Why it matters. Infrastructure growth is valuable only if the capacity eventually earns cash returns.
Source: Backblaze Q3 2026 earnings release (8-K Ex. 99.1)
Forensic #4: Convertible Financing And Outlook
A zero-coupon note avoids current cash interest but can still create future repayment or dilution. The financing should be compared with the cash it adds and the capacity it funds.
| Balance-sheet item | Value |
|---|---|
| Convertible notes issued | $201.25M |
| Capped-call payment | $17.53M |
| Long-term debt, net | $194.49M |
| Cash and securities | $230.24M |
| Q4 revenue guide | $49.8M-$50.2M |
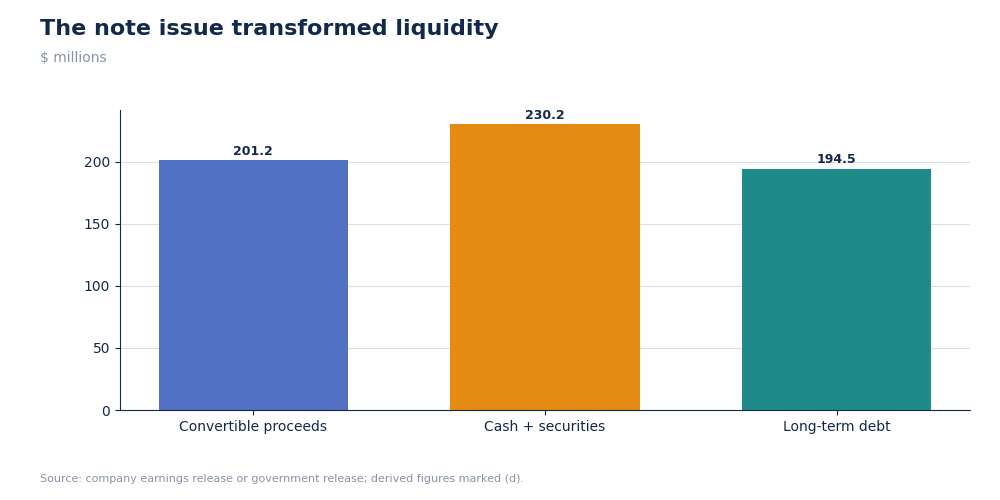
Backblaze financing and liquidity after the note issue
Cash and securities rose to $230.2M, but long-term debt rose to $194.5M. Net cash was only about $35.8M (d), so the gross liquidity headline should not be read without the new liability.
Why it matters. The financing extends the runway but transfers part of future upside to noteholders if converted.
Source: Backblaze Q3 2026 earnings release (8-K Ex. 99.1)
Valuation Snapshot
At $7.40 per share, Backblaze had a market capitalization of $449.9M. Subtracting $230.2M of cash and securities and adding $194.5M of long-term debt gives enterprise value of approximately $414.2M (d).
| Measure | Value |
|---|---|
| Share price | $7.40 |
| Market capitalization | $449.9M |
| Enterprise value | $414.2M (d) |
| EV / 2026 revenue guide | 2.33x (d) |
| EV / guided adjusted EBITDA | 7.63x (d) |
| Nine-month adjusted FCF yield | 0.42% (d) |
| Net cash | $35.8M (d) |
Investment read-through. The 7.6x adjusted EBITDA multiple looks inexpensive beside 47% B2 growth, but the near-zero cash yield shows why the market discounts that EBITDA. If adjusted EBITDA converted to cash at 50%, enterprise value would equal about 15.3x cash earnings (d); at 25% conversion it would be 30.5x (d). Cash conversion, not revenue growth alone, is the rerating trigger.
What has to be true. B2 retention must remain above 110%, capital spending must normalize and adjusted EBITDA must become free cash flow before convertible dilution becomes material.
Source: Market quote and market capitalization from the in-session U.S. equity market feed; cash, debt and guidance from Backblaze's Q3 2026 SEC exhibit. Market data: latest quote retrieved after the November 2, 2026 U.S. trading session.
Risks: What Would Break The Thesis
- Legacy decline. Backup NRR is below 100%.
- Cash conversion. Free cash flow trails adjusted EBITDA.
- Convertible dilution. Notes can dilute equity depending on terms and price.
- Capital intensity. Property, equipment and internal-use software are growing.
The case improves if B2 NRR holds above 110% and capex per dollar of added ARR declines.
What To Watch Next
- B2 revenue growth against 47%.
- B2 NRR against 115%.
- Backup NRR against 94%.
- Adjusted free cash flow after $1.9M year to date.
- Use of the convertible proceeds.

Sandeep Gupta
Independent equity research analyst publishing forensic theses on US-listed stocks. MBA, Politecnico di Milano School of Management (Milan, Italy).
Get new research in your inbox
Subscribe to receive forensic equity research the moment it's published. Free, no spam.
Discussion
Be the first to comment.